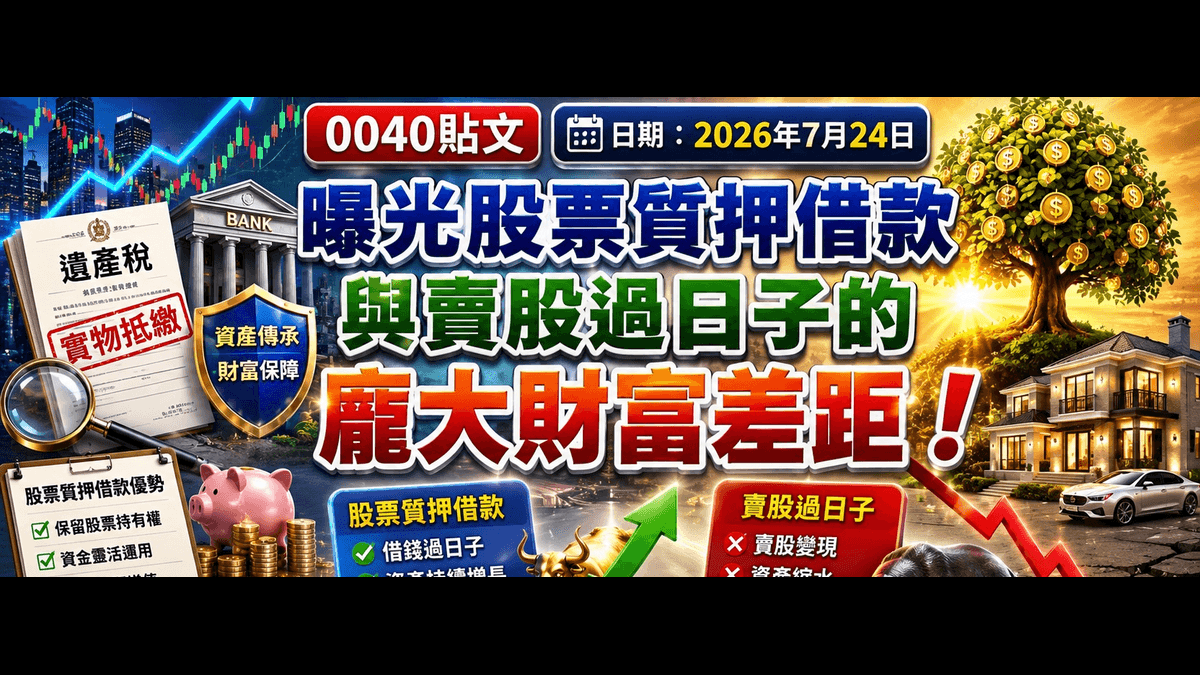
Exposing the Enormous Wealth Gap Between Stock-Backed Borrowing and Selling Stock to Live On!
Estate tax in Taiwan can be paid in kind, so heirs need not sell shares just to pay it. Funding living costs with a stock-backed loan could leave a net estate more than NT$400 million larger after 40 years—provided interest rates, loan ratios, and forced-liquidation risk are managed.
You may not know that banks in Taiwan impose a strict requirement on heirs after you pass away: if the estate includes a bank loan, property pledged as collateral generally must have the loan repaid first, or the bank must consent, before the collateral can be released, the related security rights cancelled, or the property transferred. Heirs must also pay estate tax and obtain a certificate of estate tax payment issued by the tax authority, or qualifying tax-exemption documents, before the related property transfer can be processed.
The Estate and Gift Tax Act provides a system for paying estate tax in kind. Where the requirements are met, if there is not enough cash in the estate but there is property that may lawfully be used for payment in kind, heirs may apply. So it is not necessarily the case that a large amount of cash must be prepared to complete the inheritance.
Of course, this assumes the heirs have sound investment and financial concepts and are able to use stock-backed borrowing to pay the estate tax. That way they do not have to sell stock in order to pay tax, assets and debts can be passed on smoothly, and they continue to enjoy the compounding effect of long-term asset growth.
Where the relevant rules are met, heirs may apply to the tax authority to provide security or to use other legally available procedures to transfer part of the estate first; the actual practice still depends on the law in force at the time and on the individual case. That said, if you choose to live on stock-backed borrowing, then where the relevant conditions are met you may enjoy certain financial and tax planning advantages. If the long-term investment return exceeds the cost of borrowing and the risk is properly controlled, the final net value of the estate may end up higher than with the approach of regularly selling stock to cover living expenses.
Imagine that you now hold NT$30 million and invest it for 40 years; your assets would reach NT$1,357,777,667.
However, if you choose to live on stock-backed borrowing, spending NT$1 million per year while borrowing at a 3% interest rate, then after 40 years you would owe NT$77,663,362.
In the end, the net value of your estate would reach NT$1,289,114,305. This means that even though you spent a certain amount each year, covering living expenses through stock-backed borrowing still let your assets grow substantially; compared with the case of no borrowing, your net asset value would be only NT$870,925,855.
The gap between the two is as large as NT$409,188,450! A gap like this brings considerable wealth appreciation and an advantage in passing wealth on.
(The calculation above assumes that the long-term investment return exceeds the cost of borrowing and that no forced liquidation or similar event occurs during the loan period.)
Through stock-backed borrowing you can keep more cash flow, continue to participate in the investment market, and enjoy the gains that come from asset growth. This not only makes your use of funds more flexible, it also gives you more capital during this period to take part in more investment opportunities. Compared with selling stock to cover living expenses or to pay estate tax, stock-backed borrowing still lets you keep your stock position and continue to enjoy the potential of long-term appreciation. Such a strategy provides not only short-term cash flow but also long-term growth and steady returns for your assets.
Looked at from another angle, this is an opportunity to achieve greater success in your financial planning. By covering living expenses with stock-backed borrowing and using the funds to invest, you grow your assets to an astonishing figure and push the net value of your estate far beyond what you originally expected.
Stock-backed borrowing is not suitable for everyone; you still have to consider the loan interest rate, the loan-to-value ratio, the volatility risk of the assets, and your own ability to repay. More importantly, the loan amount should keep a sufficient margin of safety to avoid facing a margin call on the collateral or forced disposal when the market swings violently.
Do not let wealth slip away because you sold stock too early. If stock-backed borrowing fits your financial situation and risk tolerance, it can become an important tool for long-term asset growth and succession. Set out on this road toward financial freedom and enjoy the freedom and happiness that growing wealth brings! Your future is in your own hands—start taking action!
Like our posts, please hit Like: Follow: Comment: Share:
Written by: James
More Posts
Omacro Comment: 'Bubbles Are Not Scary. What Is Scary Is Losing Opportunity by Not Being in the Market'
Omacro comment: 'Bubbles are not scary. What is scary is losing opportunity by not being in the market.' A relaxed talk on investing from CLEC Investment and Financial Education Academy. Post date: April 28, 2021.

Chapter 72 [Instructions on buying index without operation and never selling]
The description of what we call buying an index, not operating, and never selling, is as follows: ㄧ. Buying an index means that there will never be any problems with the target we choose. So you can never sell it. You can buy it anytime, if you have money. 2. Always hold index funds and never sell them. Unless you need money, sell as much as you need. 3. Don’t operate, that is, don’t think that the market has risen too much, so you want to sell high, wait for the low point to buy back, want to sell high, buy low, or buy low, sell high, and earn the price difference. In the end, it usually turns into chasing.
Facebook CLEC Investment and Financial Education Academy
This Facebook channel is a platform for learning about finance and investing. It offers simple, practical investment concepts and tools, along with market analysis, to help readers move step by step toward financial freedom.
Newsletter
Join the community
Subscribe to our newsletter for the latest news and updates