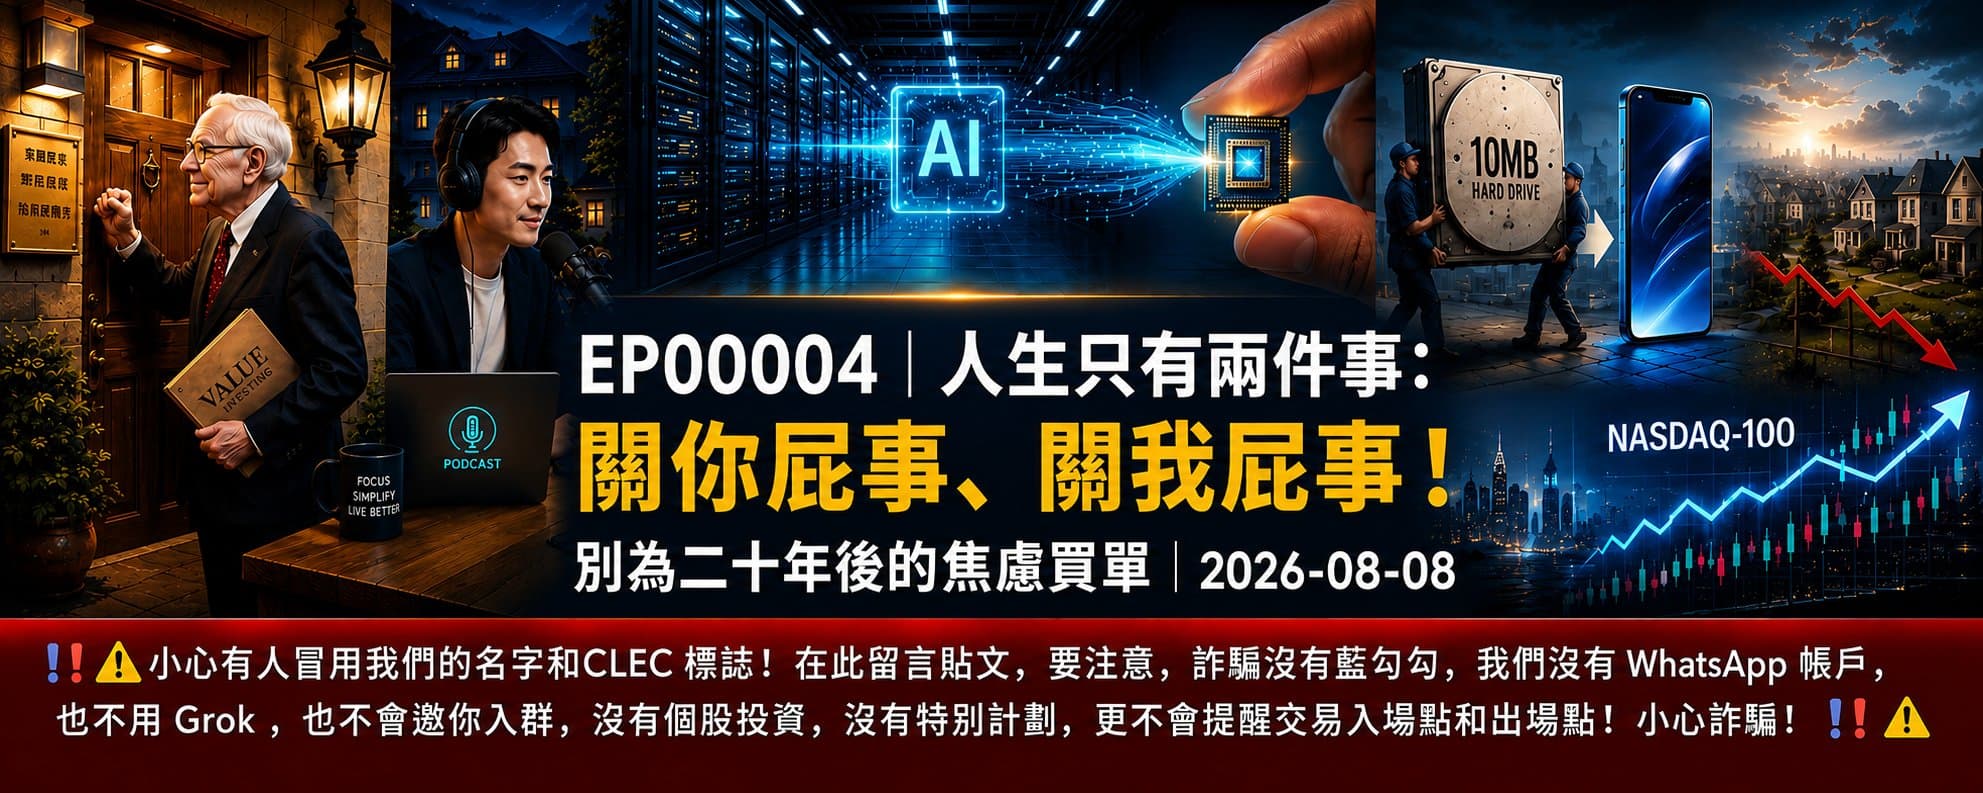
There Are Only Two Things in Life: None of Your Business and None of My Business
Episode four of CLEC James Talks: starting from the story of Buffett being turned away door to door, it lays out the "two hours, eight kilometers" rule for what deserves your attention, then turns to the miniaturization of AI, the demographic myths behind real estate, and why you should not leave more than half your income to a distant future.
-
What Buffett Knocking on Doors Teaches Us: the Two Things in Life and the Mindset of Long-Term Investing
-
None of Your Business, None of My Business! Do Not Pay Today for Anxiety About 30 Years From Now|On the Evolution of AI and the Myths of Real Estate
-
From Buffett Being Shut Out to the Miniaturization of AI: the Wisdom of Simplifying Investing and Life
-
Do Not Force Investing, Do Not Live Anxiously: Mastering the "Eight-Kilometer Rule" and Asset Allocation
https://open.spotify.com/episode/7iVmTw4CbETkIOUQgMurbR?si=tiKY8KiOSRyhcjMyHKwfcw
Hello everyone, this is CLEC James Talks, and I am James.
To begin today, let me share a story I heard this morning from a biography of Buffett.
In his early years Buffett went from door to door visiting neighbors, hoping to invite them into his investment partnership. The first time he knocked, he explained the investment plan to a married couple, and they answered, "All right, we will think about it."
The second time Buffett went and knocked, the lights inside were on but no one came to the door; he thought they might be busy. The third time he knocked again, and the couple simply turned the lights off. Only then did Buffett understand that they did not want to invest at all.
What this story shows is that even when Buffett comes to your door in person to invite you into an investment that might one day make you a billionaire, there are still people who cannot accept it, cannot agree with it, and in the end miss the chance to change their fate.
So I often say this is destiny. We do not need to force everyone to accept the same way of investing, still less to force anyone to change.
There are really only two things in life:
One is "none of your business";
The other is "none of my business."
Faced with things happening out in the world, including the news, earnings reports, unemployment rates, social events, or market swings, we should first ask ourselves, "Is this any of my business?" If it has no direct bearing on our own life and decisions, do not take it to heart.
When parents, relatives, friends, or anyone else wants to interfere in your life and demand that you do things their way, you can also ask yourself, "Is this any of your business?" Everyone has their own life and their own lessons.
The things we really need to deal with are in fact very few. Once you can tell clearly what is your own lesson and what is someone else's, life naturally becomes leisurely, rich, and happy.
Next let me talk about artificial intelligence.
Investment in AI infrastructure now runs to tens and hundreds of billions of dollars at a time; data centers get bigger one after another and consume enormous amounts of electricity. This reminds me of early IBM computers, where a single machine might occupy an entire building, a colossus in the truest sense.
When I first started working on Wall Street in 1990, a colleague called me over to help move a hard drive. I asked him, "How big is this hard drive?" He answered, "10 mega, that is, 10MB."
Phone storage today routinely runs to 128GB or 256GB, yet back then a 10MB hard drive took two people to carry. The computing power in a single phone today, placed back in that era, might not have fit into the whole of Manhattan.
Technology advances far faster than people imagine. So AI systems that today need enormous facilities and consume vast energy will not necessarily always be that way. Following the direction technology has taken in the past, equipment usually becomes smaller, faster, and more energy efficient. In the future the function of an entire AI data center may shrink into a handheld device.
Of course, this is only my imagination based on how technology develops, and it has no direct bearing on how we invest right now. We do not need to change our long-term investment strategy just because of our own predictions.
Many friends often worry about what will happen 30 or 50 years from now. I often say:
Things within two hours and within eight kilometers are the ones we need to deal with seriously; things beyond two hours and beyond eight kilometers are not worth worrying about too much.
Someone asked me, "Will America decline in the future? Is it right for us to invest everything in America? Should we diversify into other countries?"
Whether America will decline is not something I can predict accurately, and it is very likely a matter of decades from now. I have said before that if the day comes when American companies make up less than half of the world's ten largest firms by market value, perhaps that would be a turning point worth noting.
Until then, there is no need to fret every day about changes decades away. Some people worry about war; I think that rather than worrying about a war decades from now, you might as well worry about whether an asteroid will hit the earth tomorrow. None of these are things we can control today.
More importantly, do not keep paying out money now because of anxiety about uncertainties twenty or thirty years away.
Many people buy insurance because they worry about long-term care, medical costs, and illness risk three or four decades from now, and some even buy life insurance for a child the moment the child is born. But no one knows what medical technology and social institutions will look like in thirty or forty years. Future medical costs may fall sharply, and part of medical care may even be borne by the government or by new systems.
We are not saying there is no risk in the future; we are saying do not sacrifice a large amount of money and quality of life now for a distant risk you cannot pin down.
Buying a house is the same principle.
Buffett once said that spending $35,000 in his early years to buy his own house was one of the major investment mistakes he made, because if that money had gone into his business it might have grown into an enormous fortune.
But looked at another way, he bought that house after he married and had children, and his family lived in it for decades; those memories and that value in living may also exceed money.
So everyone weighs things differently. The point is not to spend nothing at all, but not to put all your money and resources into preparing for retirement.
Life now is also life, and life after retirement is also life. Life now may even deserve more attention than life after retirement. Suppose you put two-thirds of your income toward your family and your life now, and around 30% into retirement and long-term investing; I think that is already plenty. There is no need to leave more than half of your income entirely to a distant future while making yourself and your family live very hard right now.
Housing should also be kept within reason. Once you have enough assets, buying a home according to your needs is of course perfectly fine. But many friends who sold their house and switched to renting a bigger, more comfortable one have found that their quality of life is far better than before.
Conventional thinking always tells us to work hard, save a down payment, buy a house, and pay the mortgage; the more aggressive buy three, five, or even more than ten houses to rent out. But buying more does not mean you become freer. Rental income may be offset by loans, taxes, maintenance, and management costs, and in the end you are just carrying more heavy assets and can never retire.
A friend who studied finance and works in accounting had clients who mostly invested in real estate, and he himself had bought nearly ten properties. Later, after encountering our way of thinking about investing, he began selling the real estate, freeing up capital and moving into a U.S. Nasdaq-100 index fund, hoping to build a simpler long-term way of investing so that he could retire a little earlier.
One of the biggest long-term problems with real estate is the gradual decline in population. In many places deaths already outnumber births. When families have fewer and fewer children while the previous generation leaves behind more and more houses, who will live in those houses in the end?
A couple may in future inherit several houses left by both the husband's and the wife's parents, while they themselves may have only one child, or none. With population falling continuously and houses still increasing, long-term supply and demand may naturally change.
These projections will not necessarily all come true, but even if they do not happen there is no need to be afraid. As long as you keep investing in the Nasdaq-100 index fund, which has long-term growth behind it, then when you have accumulated enough assets, buying a house later will still be easy.
The development of artificial intelligence has also gone beyond what many people imagined. Today a great deal of short-form video, drama, acting, dubbing, and background music, and even merchandise, can be produced by AI. Some AI characters are already so lifelike that it is hard to tell what is real.
Once AI began to be able to write code, many entry-level programming jobs were affected. In future the work of actors, singers, lyricists, composers, and editors in film and television may also change enormously. This is a tide of the times that cannot be stopped.
Therefore everyone should learn to use artificial intelligence, but let AI add to your abilities rather than let yourself lose the ability to think.
I still take my own notes, record, and think every day. After recording, I let AI help organize the transcript, produce the video, do the voiceover, or upload it. That is what AI empowerment means: raising our efficiency and output, not letting artificial intelligence replace the value of human beings themselves.
Some occupations may gradually disappear in future, and new jobs will appear. What we should do is not to fear but to learn to use new tools and adapt to the changes of the times, so that we are not made obsolete by the tools.
Investing is the same. We do not need to guess the market every day, nor keep predicting what the world will be like decades from now. Just use the simplest, most systematic method, get your asset allocation right, keep it for the long term in assets with growth behind them such as the Nasdaq-100 index fund, and then keep your time for yourself and your family and live each day well.
There are only two things in life: none of your business, none of my business.
Things within two hours and within eight kilometers we handle properly; things beyond two hours and beyond eight kilometers, and all that uncertainty-filled anxiety about twenty or thirty years from now, we let go of.
Life really is not that complicated. Tell your own lessons apart from other people's, do not pay for distant fears, make good use of artificial intelligence, simplify your investing, and keep your time and resources for the life you are living now.
Do these things and both your life and your investing will become a great deal easier.
All right, let us stop here for today. Thank you all, and see you next time!
More Posts
The Difference Between Switching and Speculative Trading
The Difference Between Switching and Speculative Trading. Written on August 29, 2018. I have repeatedly reminded everyone not to trade after buying, but everyone needs to understand the difference between switching and speculative trading.
Is Buying a Home Important? My Homebuying Experience and Financial View
The author shares homebuying experiences in Taiwan and the United States, and reflects on location, cash flow, leverage, retirement, and renting.
Chapter 95: The Process of Becoming Wealthy, a Life of Freedom
Dear Teacher James, I sincerely say hello to you and wish you good health and all the best. As a follower of yours, I hope to share with you what I have experienced over the past year. First, I want to mention 2022. That year was full of challenges and opportunities for me. In December 2021, I heard about the investment opportunity in CLEC and made the bold decision in January 2022 to go all-in on the market and choose to invest at the high point of the stock price
Newsletter
Join the community
Subscribe to our newsletter for the latest news and updates