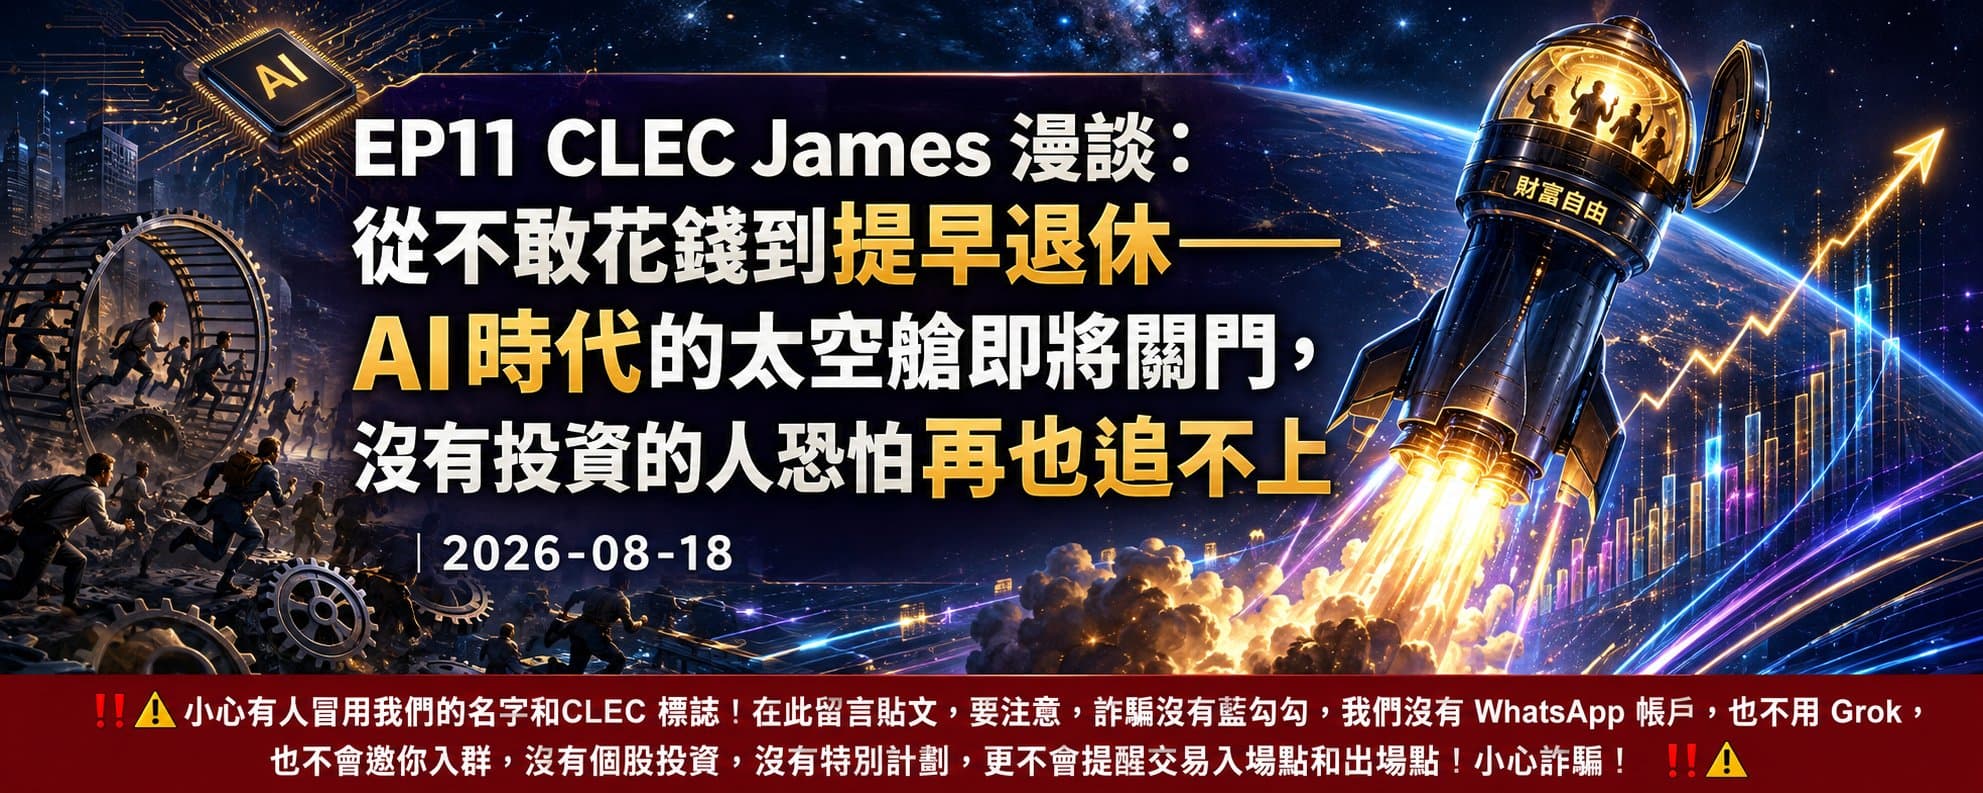
From Not Daring to Spend to Retiring Early: In the AI Era the Capsule Hatch Is About to Close
Episode eleven of CLEC James Talks: a student goes from not daring to spend, to buying a car on credit and speaking up at work, and now wants to retire; plus how to handle a spouse's insecurity. It closes with a rocket-and-capsule analogy: the door to investing is slowly shutting.
The following is the podcast transcript:
Hi everyone, this is the CLEC James Talks channel, and I am James.
Our transcripts are published as articles on X, and the podcast is uploaded to Spotify and Apple Podcasts. Just search for "CLEC James Talks" on those two platforms and you will find our channel, so from now on we will not post separate Spotify or Apple Podcasts links; anyone who wants to listen can find us with a search.
Today I want to talk about what one student shared with me.
This student used not to dare spend money, and is now learning how to spend, following the teacher's way and experiencing a wealthy life.
He said that in the past he did not even dare to spend, still less imagine that one day he would spend a lot on a good car. Now he is not only learning to spend, but also learning to live on other people's money.
When you watched the videos before, you often heard me say, "Borrowing money to spend really feels great!"
In fact, borrowing to invest through credit loans, mortgages, or stock-backed loans also feels great; but taking borrowed money and using it directly to enjoy life is a different experience again.
Seeing other students beginning to feel the joy of spending, he wanted to join in and feel it for himself. So he took out a loan and bought a new car, and afterwards found it really did feel great!
He wrote to share that he is gradually moving toward a life that is both wealthy and knows how to spend. It is only that the sense of scarcity built up over many years is still hiding in a corner of his heart. He keeps feeling his assets need to be a little larger before he can spend with real confidence.
I often say you do not have to borrow one large sum to spend all at once. You can start within what you can psychologically bear and practice how to borrow in order to enjoy life.
For example, borrow one or two hundred thousand through a stock-backed loan for a trip; or borrow twenty or thirty thousand dollars to pay taxes. Start with an amount you can accept and gradually practice borrowing to spend.
This friend also shared something that happened recently at work.
His big boss, that is, his direct supervisor's superior, had a talk with him and said, "You seem a bit restless in your work lately."
At first he could not work out why the boss said that; later he realized it might be because he had been speaking more directly to his immediate supervisor lately, and had grown bolder about saying "no" to the boss.
He recalled that in the past, in order to earn his keep, when he met something unreasonable he would usually swallow his anger and let the grievance go.
Now, because his assets have grown and he has confidence, and has even come close to or reached the minimum retirement threshold, he has begun to dare to tell the boss the truth and to say what he thinks directly. That change may be something his immediate supervisor is not used to.
If his assets had not given him enough confidence, he might still be as deferential and accommodating toward the boss as before.
His mindset really has begun to change.
He knows that when assets reach 15 to 17 times annual expenses, the basic conditions for early retirement are already in place. He did the arithmetic and found he may already have reached that goal.
So he tested the waters a little with his husband and told him, "I should be able to retire."
To his surprise his husband firmly objected.
This is in fact quite normal. When ordinary people hear that someone will retire at a young age, the first reaction is usually, "How do you have the nerve to retire?"
Going from a dual-income household to a single-income one, the person who keeps working may feel more psychological pressure, especially men.
Sometimes people feel a husband is tight-fisted or particularly stingy. In fact many husbands simply feel they must carry the responsibility for the family, and therefore feel relatively insecure.
So his husband asked him, "Retiring this young, what are you going to do? What is there for you to do?"
This friend knows that what his husband is really worried about may not be what he will do after retiring, but that his husband feels his own salary is not enough to support the whole family.
What his husband may be thinking is, "If you stop working, how am I going to support the family from now on?"
What we want to say here is this: whether or not you can retire right now, simply knowing that you are moving steadily along the right investing road means you will certainly have the chance to retire early in future, and will not have to work into old age or work until you die. Just knowing that makes your heart much lighter.
You thought you were a worker sentenced to life imprisonment, and then one day the judge tells you, "You only have seven years left before you can walk out!"
That feeling is hope.
You finally know that one day you can leave this rat cage of work.
Knowing that retirement is something you can look forward to, that early retirement really will come, is not only a relief in assets and in daily life; it is also enormously helpful to our physical health, our mental health, and family harmony.
If a person runs every day in a rat cage with no end in sight, their temper, their emotions, and their physical condition will sooner or later go wrong.
We are very glad that through our channel people's lives are becoming calmer and their families more harmonious, because what they used to worry about no longer exists.
You know that one day you will certainly be able to retire.
In fact, after retiring we can do nothing at all.
Some will ask, "If you retire, what are you going to do?"
We can do nothing at all!
I have been retired for more than twenty years; this is my 22nd. Every morning when I get up, the first thing I do is brew a cup of coffee.
Sometimes I wake at five or six in the morning. My motivation for getting up is the thought that I can finally brew another cup of fragrant, rich, good coffee.
I am woken by that cup of coffee.
Every morning I think, "Wonderful, I get to get up and drink a good cup of coffee again!"
I can do nothing at all.
The outside world thinks a person must be doing something; that is the thinking capitalism instilled in us, and it is also DNA humans inherited in order to survive.
In ancient times humans had to go out and look for food; if they did not, they might starve that night.
But now we can not work and still have money to spend. We can escape the rat cage of capitalism, and we can also overcome the DNA inherited from ancient times for the sake of survival.
I hope that one day this human DNA of "you must keep working to survive" can mutate, so that we understand: we can in fact do nothing at all, and no longer worry about survival.
We should build new DNA: letting your assets work matters more than working yourself.
When the AI era arrives, all of this may become even more normal. If human attitudes do not change, people may be very ill-adapted in future, because by then there may not even be jobs.
Recently I thought of a very vivid analogy.
Elon Musk's rockets may have two or three stages. At launch, the first stage provides enormous thrust, and once its fuel is spent it separates and falls back to the ground; the second stage keeps pushing, and after completing its task it too separates. What is truly valuable at the end, what can reach space, is the capsule at the very top.
With artificial intelligence developed as far as it has today, only those who have already invested in artificial intelligence and the technology industry have a chance to sit in that topmost, most valuable capsule and not fall with the times.
Those who have not invested in assets may be like the nine engines on the first stage. They burn themselves up, push the capsule upward, and after completing the task fall back to the ground, never truly flying into outer space.
The second stage too will eventually separate and be discarded.
Only those who have already begun investing have a chance to sit in the capsule. In future, once the capsule separates from the rocket and flies toward the universe, those who did not invest may never again have a chance to get in, and can only stay below forever as fuel tanks.
There is nothing to be done about that.
AI companies now have market values of one or two trillion dollars. Ten years from now some may reach ten trillion dollars, or even more.
When the assets of investors like us grow tenfold or a hundredfold, how will people who start investing five or ten years later ever catch up with us?
They may never catch up again.
They can only go on serving as the engines that push the rocket, with no way to sit inside the capsule.
That is why I say that with AI developed as far as it has, the door to investing is slowly closing. The number of people who can get into the capsule is limited, and the hatch is about to shut. Once the hatch closes completely, those behind may never catch up.
Of course this friend also does not dare tell his husband exactly how much he has.
Because he heard Penny's story last time. In order to advise her boyfriend to invest, Penny showed him her assets and let him know she had made a lot of money. Afterwards the boyfriend wanted to borrow against real estate and asked Penny to endorse the loan and act as guarantor, and even hoped she would take on more of the living expenses.
Because of that example, this friend does not dare tell his husband how much he actually has now.
When husband and wife have different ideas about investing and money, it really is a headache. Some people simply will not listen, and that may also be fate.
He has already brought correct and valuable information right to his husband's lips, and his husband still will not open his mouth and take it.
This friend wants to retire, so he asked me how he should arrange things.
In fact their finances are already relatively independent, with each side bearing household expenses separately or sharing them. Since the existing arrangement works well, do not deliberately change it.
He also does not have to tell his husband about all his assets, still less disclose the real figure. He only needs to tell his husband, "I have done some investing and made a little money." That is enough.
Because the two of them think differently about investing and money, letting the other side know the real asset figure may serve no purpose at all.
Just keep the existing proportions in which each side covers household expenses.
The other party uses capital less efficiently. If you let him know you have more assets, he may be unwilling to spend his own money, saving all of it and preferring to spend yours, which is used more efficiently. That is not good for the family as a whole.
Of course, in law, rules about marital property may apply to a couple. Not telling your spouse your asset figures does not mean legal property rights disappear as a result.
A person can retire because employment income has become a vanishingly small share of total assets.
Everyone should realize that if you already have 15 or 17 times annual expenses, your assets may still grow by another zero, two zeros, or even three zeros in future.
Add one zero and 15 times annual expenses becomes 150 times; add two zeros and it is 1,500 times annual expenses.
Could you possibly live to more than a thousand years old? Of course not!
So when you have assets equal to 15 times annual expenses, you should slow down and start preparing more for your physical health, your mental health, and family harmony.
Stop haggling over a salary that is vanishingly small compared with your total assets, and stop working yourself to the bone for that little salary.
This friend could tell his husband:
"Although I have retired, I will keep covering the household expenses I was supposed to cover, just as before."
That will put his husband's mind at rest.
His husband thinks investing will not necessarily succeed. In the short term it is hard for us to make him believe through explanation alone. After all, before the results actually appear it is hard to prove that the future will certainly succeed, so it still takes time.
Even in retirement you can go on covering the household expenses you were supposed to cover. Sometimes you can also volunteer to pay and take the whole family on a trip, so that your husband gradually feels what a truly wealthy life is.
You do not necessarily need to prove how high your investment returns are, nor do you have to lay out your real assets in full for your spouse.
For example, when the family occasionally goes out for a big meal, you can say, "Never mind, dinner is on me today!"
Expenses that your husband was supposed to cover, covered by you now and then, will make him very happy and love you more.
As what you contribute to the family quietly grows, the relationship between you will also keep improving.
If your husband wants to buy something but cannot bring himself to spend the money, you can tell him, "Never mind, I will buy it for you as a gift!"
The relationship will grow more and more harmonious.
After retiring, first take living expenses from your retirement assets at a reasonable withdrawal rate. However much of the household expenses you were supposed to cover, keep covering. If there is money left over, you can use it to look after yourself, look after your children, or treat your husband to a big meal.
"Let us go out to eat today, my treat!"
It is that simple.
Our students are all wonderful; every one of them can become the great tree of their family.
We already understand investing and money management, so our financial planning, our psychological strength, and our spiritual energy are all greater than most people's.
We are not only the great tree of our household but the great tree of the whole extended family; not only a stabilizing force financially, but a stabilizing force spiritually.
As long as a family has a great tree like us, that whole family has a chance to be prosperous forever.
That is what I wanted to share with you today.
First, this friend took out a loan and bought a good car, and felt the joy of borrowing and spending.
Second, as his assets grew he became bolder about speaking the truth at work, no longer bowing for five pecks of rice.
Third, he is preparing to retire but his husband feels insecure. That is all right: by continuing to cover household expenses and moderately demonstrating a wealthy way of living, he can gradually make his husband comfortable with his retirement.
Finally, please remember this:
Those who have already begun investing are like people seated in a capsule flying into outer space; the rest may only serve as the rocket's engines, burning themselves up every day and falling back to the ground again and again. Their function is merely to push the capsule we are riding in toward outer space.
Starting to invest now is extremely important, because this investing window may be gradually closing. The future growth of AI and technology index funds may well exceed human imagination. Those who start investing too late may never catch up.
All right, that is where today's CLEC James Talks ends.
See you tomorrow, bye-bye!
More Posts
Chapter 63 [Investment Concept] - The market is bullish, hold on tight! 】
It is very simple to become rich by investing. As long as you accept the correct investment concept and never sell, you will be rich. Being rich is that simple. Buffett once said: [Patience makes you rich] This is a very simple statement, but few people do it because not many people know how to invest correctly. But few actually understand it, and even fewer do it, and many senior CLEC students don't do much (it's not easy). No matter whether the market goes up or down, hold on to your shares. Lose your position on a bullish rally (have no position
Chapter 33 [Ability to invest in individual stocks]
Any position in a company that is more than a CEO, an individual is specialized in one or two jobs, but the CEO of a company is different. A CEO is not only familiar with the company's products, but also has a vision of the market, long-term dreams, financial knowledge, and strong management and communication skills. Only this person with such a comprehensive ability can be competent for the CEO's job. A successful individual stock investor needs to have the same skills as a CEO
Global Investment Platform eToro Is Not a Legal Taiwan Securities and Futures Firm, and the FSC Has Deemed It Illegal
The post warns about account risks at eToro and Robinhood and stresses safety, legal compliance, and proper investment channels.
Newsletter
Join the community
Subscribe to our newsletter for the latest news and updates