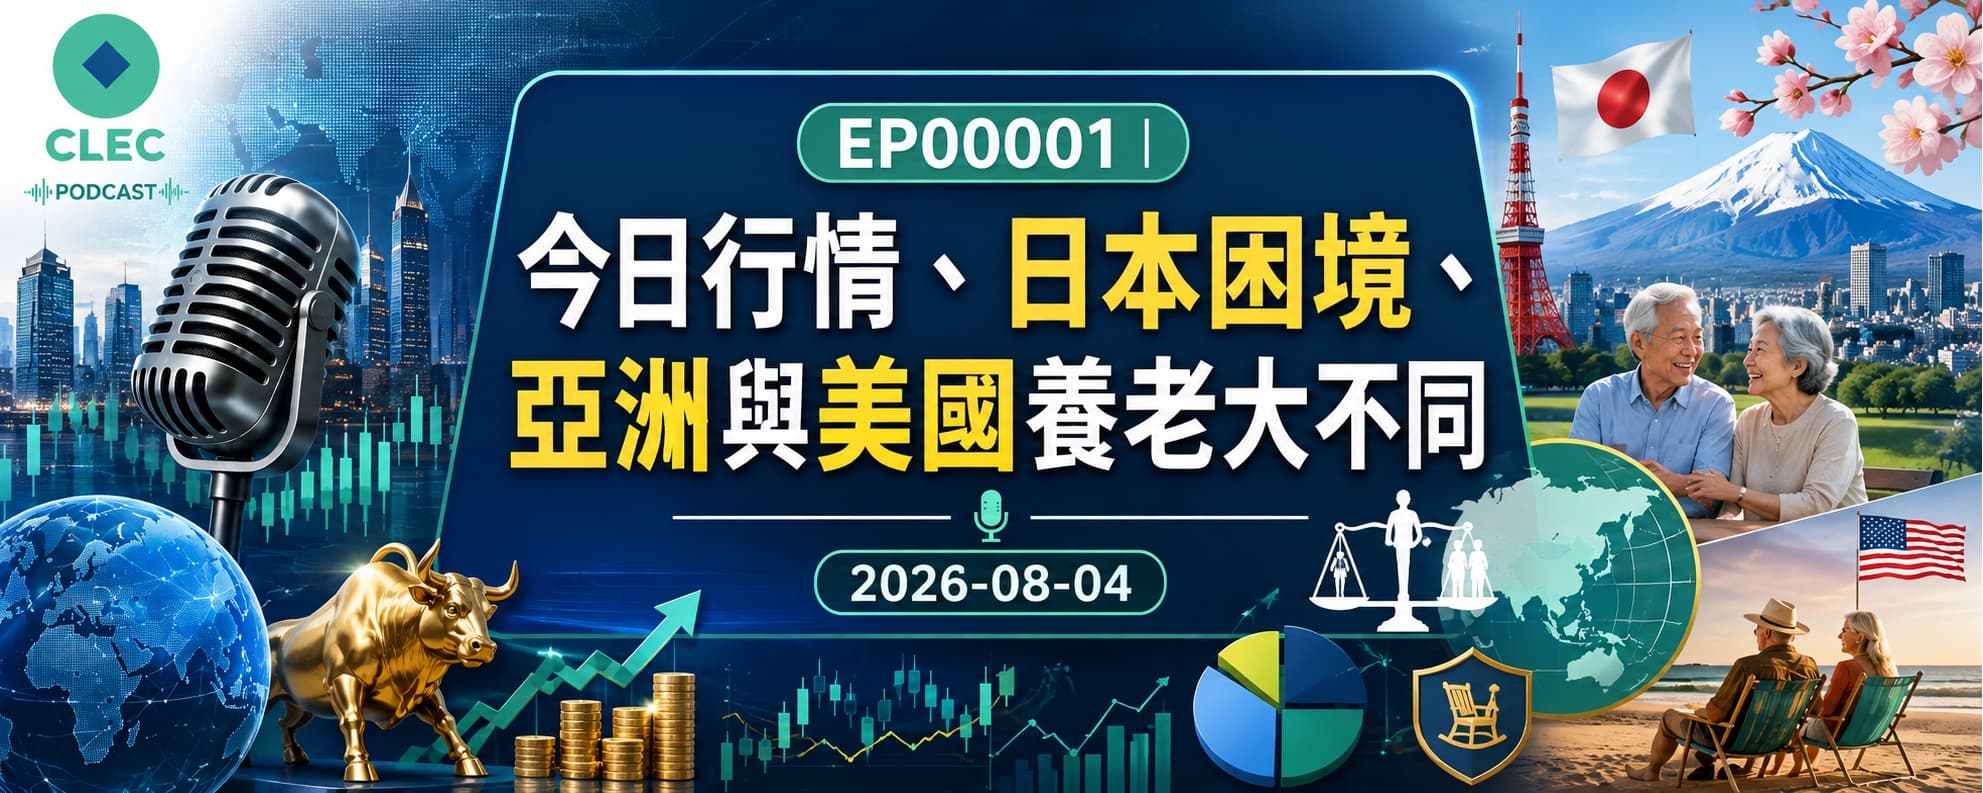
CLEC James Talks EP1: Today's Market, Japan's Predicament, and Retirement in Asia vs. America
Episode one of James's new podcast channel "CLEC James Talks": the purpose and format of the show, a recap of U.S. equities and the yen on August 4, and an in-depth comparison of the policy mistakes behind Japan's property bubble with the cultural and institutional differences in how Japan and America handled debt deflation.
This audio recording is episode 1 of the podcast channel "CLEC James Talks," which James has launched. Below is a summary of the key points from the recording:
https://open.spotify.com/show/0341y5vfK57DF4zMsbAmDL?si=8r5KAYnATSCZ94q3nUIzng&utm_source=copy-link
Background and Purpose of the Show
Channel positioning: The show is called "CLEC James Talks," and its format is like a fireside chat or a casual conversation among friends.
Original intention: Besides the long-form investing content that comes out every Saturday, and at the request of many friends and students, the hope was to have a platform for sharing small things from daily life and a wider range of topics.
Show format: There is no fixed theme or segment for now; the first few episodes will be conducted in a more casual, free-flowing conversational style.
EP00001|Today's Market, Japan's Predicament, and How Retirement Differs Between Asia and America|2026-08-04
Stock market performance: U.S. equities (as of the August 4 close) were strong. The Nasdaq index rose 2.59% and QQQ gained 3.4%, with tech giants such as Apple, Tesla, Nvidia, and Microsoft broadly higher.
Currency moves: The U.S. dollar fell about 3.7% against the Japanese yen over the five days of that week, a rather rare and powerful appreciation for the yen.
Topic of Discussion: Japan's "Lost Three Decades" and a Comparison of How the U.S. and Japan Handled Property Bubbles
In a discursive style, the speaker analyzed in depth the different policies and cultural differences between Japan and the United States in the face of a property bubble:
1. The Causes of Japan's Property Bubble and Its Policy Mistakes
Scale of the bubble: At the peak of the bubble, the market value of real estate in the Tokyo area alone could have bought all the property in the United States.
Policy contradiction: With the yen appreciating and corporate exports blocked, the Bank of Japan did not raise rates in time to cool the overheated housing market and instead chose to cut them, which drove even more money into real estate and aggravated an enormous asset bubble.
2. Cultural and Institutional Differences in How the U.S. and Japan Handled "Debt Deflation"
Japan (debt deflation and cultural baggage):
Cultural factors: Under the influence of Eastern culture, society broadly regarded bankruptcy as shameful, so companies and individuals mostly chose to grit their teeth and carry the debt.
Outcome: Banks did not fail, and individuals kept paying mortgages they could never fully repay (for as long as 30 years), so the whole population dared not spend and companies dared not expand, sinking into a long period of "balance-sheet deflation."
The United States (how the subprime crisis was handled):
Government backstop: When the subprime crisis broke out in 2007–2008, the U.S. government and central bank moved quickly, packaging up and buying all of the banks' bad debt to help the banking system "clear its books."
Institutional mechanism: Individuals and companies that could not cope could file for bankruptcy (such as Chapter 11), hand the property back to the bank, and start again with the debt wiped out. Spending power therefore recovered quickly, and the economy bottomed and rebounded within little more than a year.
Author
Categories
More Posts
Chapter 57 [Investment Philosophy] - Successful Investors
To become a successful investor, you must understand economics, theory, history and psychology. Among them, only [psychology] is the most difficult and the most critical part to success. The most critical reason why psychology has become an investment is that the evolutionary process of our human hunting is animal behavior that focuses on short-term risks (worrying about tigers and lions; rather than focusing on long-term returns. Human genes that do not worry about short-term risks cannot survive), and investment is a market that completely opposes the psychology of human survival. [Investment Psychology] Unable to Complete
Facebook Reader Question: Why Do We Only Recommend U.S. Index Funds, Not Global Indexes or Emerging Markets?
The reply argues that U.S. index funds such as QQQ and SPY have stronger long-term returns and recovery ability than emerging markets and commodities.
Chapter 16 [Interview with Teacher Meixiang: Dialogue with Money] Part 5 of 6: How to become rich when you have nothing!
"Exclusive Interview with Teacher Mei Xiang: Dialogue with Money" 6-5 (03/02/2023) How to be rich when you have nothing! I have also thought about how I can earn another 100 million or more when I have nothing now, and then earn back my wealth. First of all, you must find a job. No matter how much your income is, as long as you have income, you must be able to save money every month. This is the starting point for getting rich from poverty. After accumulating capital, you can earn more. It’s simpler now than it used to be, there’s a lot of sharing now
Newsletter
Join the community
Subscribe to our newsletter for the latest news and updates