00682
Vacation Home Sold! You have too little cash: if the market drops 85%, you may go bankrupt
Short
Vacation Home Sold! You have too little cash: if the market drops 85%, you may go bankrupt
A stress test examines US$9.2 million with 98% Nasdaq exposure, about 1% cash-like assets, and a US$700,000 pledged loan. The speaker uses an 85% decline scenario and targets 30% liquidity.
10:49
00682
55-year-old single mother in the financial industry: From anxiety to 100 million in 4 years, the last hurdle is retirement
Short
55-year-old single mother in the financial industry: From anxiety to 100 million in 4 years, the last hurdle is retirement
A 55-year-old single mother in finance reports changing her approach in 2021 and reaching NT$100 million four years later using Nasdaq funds, reserves, leverage, and pledged credit. The result does not prove causation.
7:14
00682
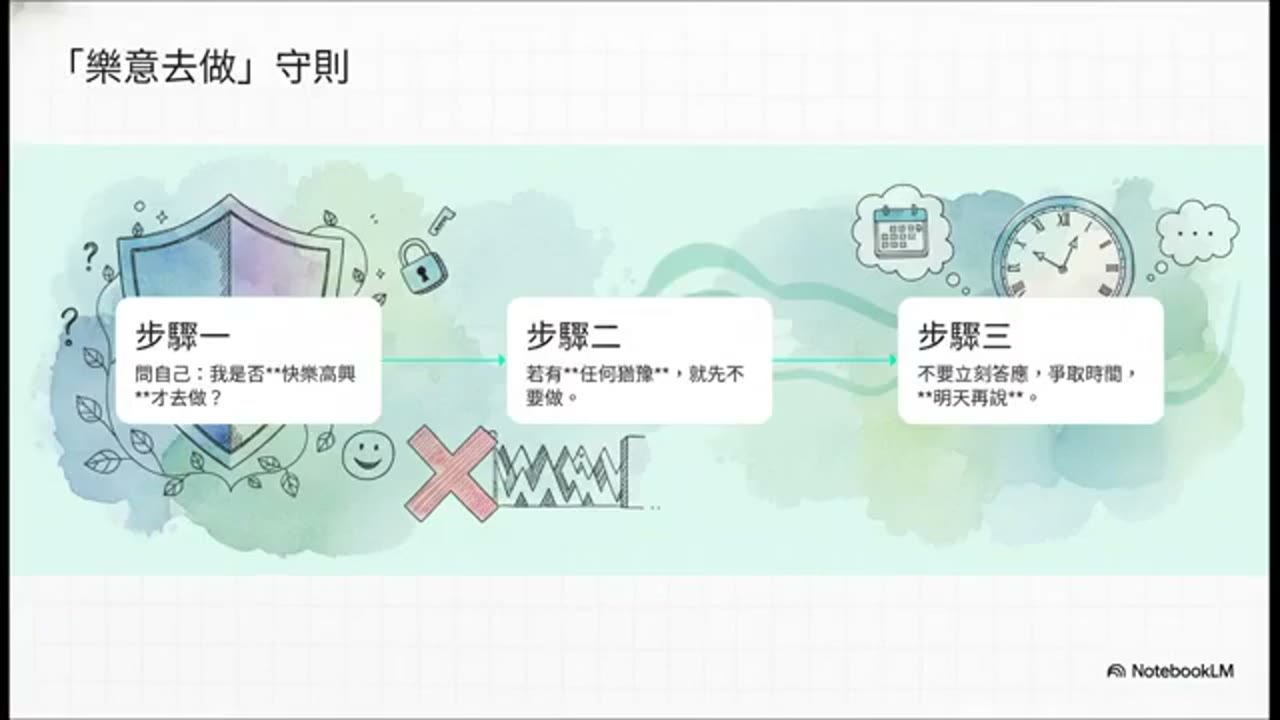
Think about yourself first, you can regret it even if you don’t like it: learn the courage to say no in the workplace
Short
Think about yourself first, you can regret it even if you don’t like it: learn the courage to say no in the workplace
A long-tenured manager reluctantly accepts an unexpected team transfer, then calls back to decline. The speaker’s boundary framework checks willingness, pauses when unsure, and asks for decision time.
5:06
00681
Plant the seeds of wealth into children’s hearts: let them know what investment is from an early age
Short
Plant the seeds of wealth into children’s hearts: let them know what investment is from an early age
A student reflects on resisting market noise and FOMO through long-term focus, discipline, and emotional control, then encourages pupils to begin investing with RMB1,000 a month.
7:25
00681
Internal friction in family investments hurts the most: Don’t argue in front of your children
Short
Internal friction in family investments hurts the most: Don’t argue in front of your children
A couple’s conflicting investment styles leave money idle and expose their child to repeated arguments. The speaker prioritizes ending conflict, rebuilding trust, and using long-term records instead of winning.
7:04
00681
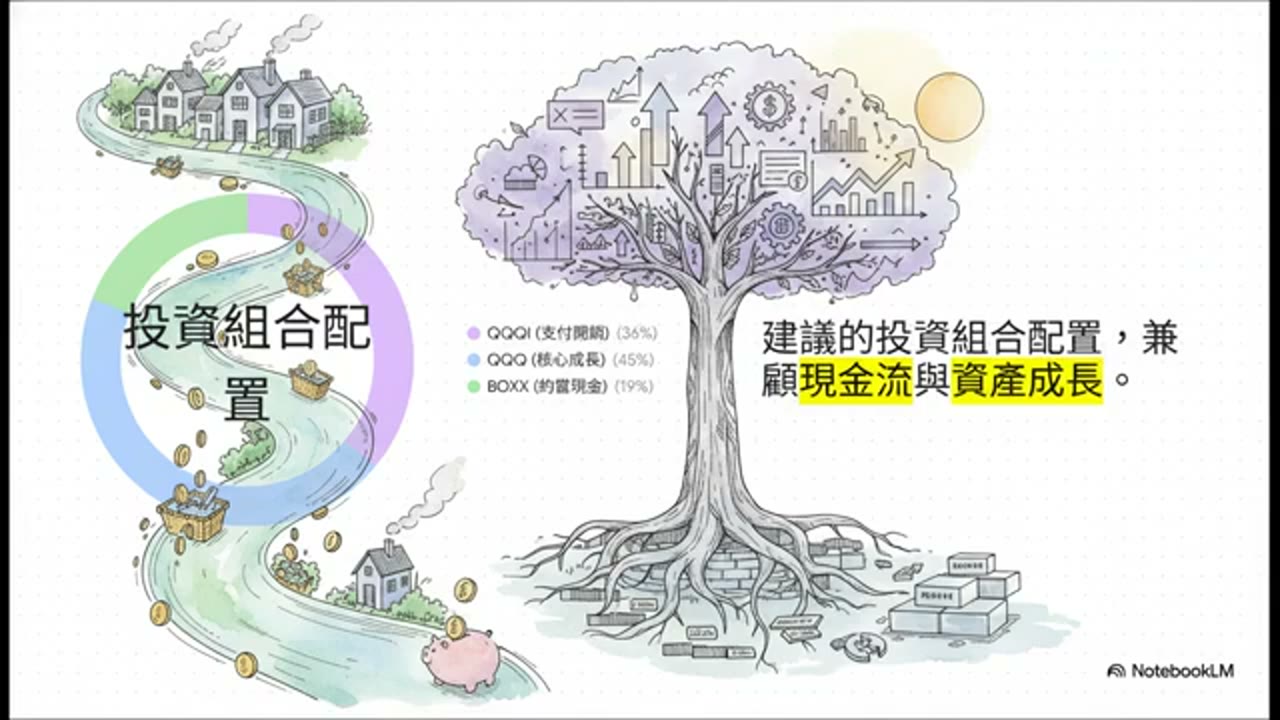
Don’t put cash around in Roth; can you retire? Calculate the withdrawal rate first and then decide
Short
Don’t put cash around in Roth; can you retire? Calculate the withdrawal rate first and then decide
A 56-year-old couple with US$3.71 million and US$160,000 of annual spending calculates a 4.31% withdrawal rate, then considers a 19-year Roth conversion and a QQQI, QQQ, and BOXX allocation.
8:48
00681
That day I was laid off, but for the first time I truly breathed a sigh of relief and took back the control of my life: How to build a cash flow defense line with 13 million assets
Short
That day I was laid off, but for the first time I truly breathed a sigh of relief and took back the control of my life: How to build a cash flow defense line with 13 million assets
The video reviews a laid-off single worker with about NT$13 million in assets, NT$1.8 million in debt, and payments above NT$30,000 monthly. The speaker’s cycle, retirement, and income claims remain case estimates.
31:38
00680
Going to work in the United States? Think clearly first: your children need to be with you, don’t delay retirement
Short
Going to work in the United States? Think clearly first: your children need to be with you, don’t delay retirement
A 50-year-old semiconductor professional with about NT$50 million weighs a U.S. job against family separation, delayed retirement, and college tuition of US$70,000–80,000 a year.
7:09
00680
True wealth is to leave time for the most important people
Short
True wealth is to leave time for the most important people
The video asks how to use time once investing becomes passive, organizing the speaker's philosophy around family, restorative solitude, continued learning, and selective relationships.
5:39
00680
You can get married, have children, and retire: the key lies in cash flow design
Short
You can get married, have children, and retire: the key lies in cash flow design
A couple with NT$8.5 million, NT$60,000–70,000 in monthly dividends, and a partner earning over NT$50,000 considers marriage, children, and a QQQI-centered cash-flow plan.
6:49
00680
All the monthly income of 9540 is used to pay the loan: How to save retirement cash flow? First high dividend of 480,000, then allocation of 70_30
Short
All the monthly income of 9540 is used to pay the loan: How to save retirement cash flow? First high dividend of 480,000, then allocation of 70_30
A 44-year-old single mother has RMB800,000 in savings, RMB2.84 million in debt, RMB10,000 monthly income, and RMB9,540 loan payments. The video proposes a two-part allocation.
6:41
00679
No need to save 50 times! 7.5 million QQQI can generate 900,000 annual cash flow
Short
No need to save 50 times! 7.5 million QQQI can generate 900,000 annual cash flow
A 43-year-old entrepreneur with a NT$75,000 monthly gap is modeled using NT$7.5 million in QQQI and an assumed 12% annual distribution to produce NT$900,000.
7:41