00583
Staking Spring Movement: Use a little bit of PAL first to experience the sense of security of "you can spend money without selling stocks"
Short
Staking Spring Movement: Use a little bit of PAL first to experience the sense of security of "you can spend money without selling stocks"
A viewer moves from resisting securities-backed borrowing to exploring PAL risks. The speaker frames PAL as a cash-flow tool for spending without selling assets and suggests a small trial, while contract risks remain.
3:25
00582
The truth about not being able to raise funds: Only by accumulating step by step can you be safe until retirement
Short
The truth about not being able to raise funds: Only by accumulating step by step can you be safe until retirement
Addressing mainland Chinese investors, the video opposes using margin to buy 513100. A RMB500,000 example with a 30% market decline illustrates leverage, interest, and forced-sale risk.
3:03
00582
Is the Roth ratio too low at the age of 57? 18-year conversion plan makes your tax safer
Short
Is the Roth ratio too low at the age of 57? 18-year conversion plan makes your tax safer
A 57-year-old lists Roth, traditional retirement, and brokerage assets and asks about a post-employment 401(k) rollover. The speaker outlines an 18-year Roth conversion concept of roughly $120,000–$130,000 annually.
1:57
00582
From short-term to long-term: 00662/QQQ allows me to go to work with peace of mind and become rich steadily
Short
From short-term to long-term: 00662/QQQ allows me to go to work with peace of mind and become rich steadily
A Taiwan employee describes moving from short-term trading to long-term 00662 or QQQ holdings and says nine friends invested in 00662. The video separates her experience from the speaker's allocation and PAL framework.
5:09
00582
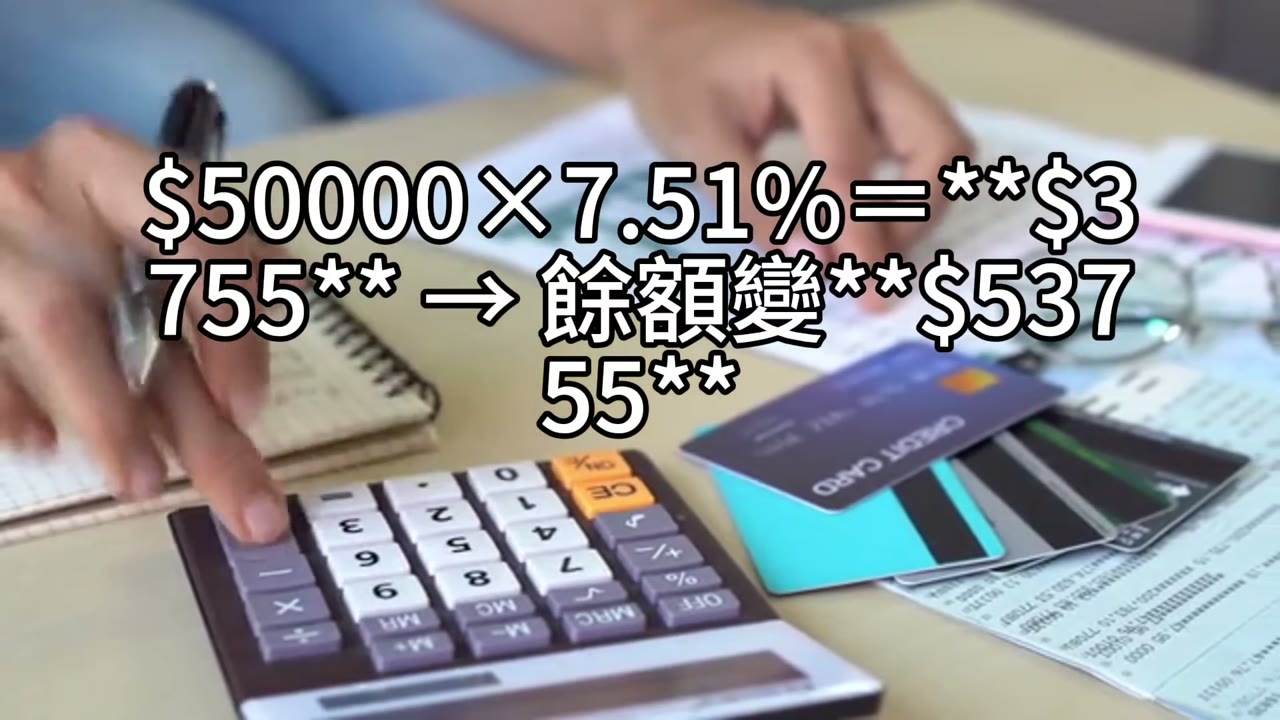
Do I need to pay PAL interest? Use 433 cash interest to "offset interest". If the maintenance rate is sufficient, you don't have to dig out your pocket.
Short
Do I need to pay PAL interest? Use 433 cash interest to "offset interest". If the maintenance rate is sufficient, you don't have to dig out your pocket.
The video says PAL billing and interest capitalization depend on the contract and uses hypothetical $900,000 assets and a $50,000 loan to compare cash income, borrowing cost, and maintenance risk.
6:27
00582
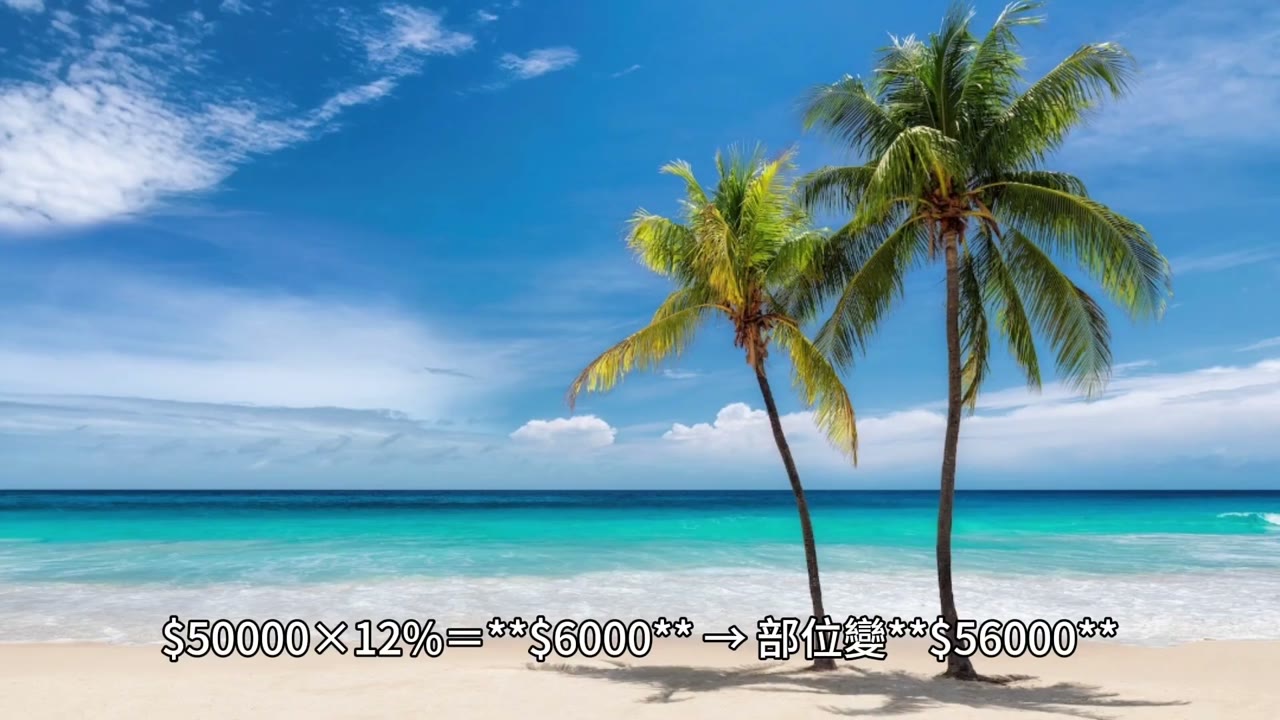
Do I need to pay PAL interest? Use 433 cash interest to "offset interest". If the maintenance rate is sufficient, you don't have to dig out your pocket.
Short
Do I need to pay PAL interest? Use 433 cash interest to "offset interest". If the maintenance rate is sufficient, you don't have to dig out your pocket.
The video explains that PAL payment and interest capitalization depend on the contract, then uses hypothetical $900,000 assets and a $50,000 loan to compare cash yield, borrowing cost, and maintenance risk.
6:30
00581
Don’t let your children study abroad to ruin your retirement: Prioritize cash flow, the correct path for long-term fixed investment in 00662
Short
Don’t let your children study abroad to ruin your retirement: Prioritize cash flow, the correct path for long-term fixed investment in 00662
A 50-year-old Taiwanese teacher plans to retire at 58–60. The household earns about NT$90,000 and spends NT$70,000 monthly, while managing co-owned homes, a presale mortgage, and possible overseas tuition.
7:49
00581
Hotel Life and Rich Thinking: The Secret to Continuous Growth of Assets
Short
Hotel Life and Rich Thinking: The Secret to Continuous Growth of Assets
A student sold a home three years ago and now lives in hotels. After a later sale created about US$600,000 in long-term capital-gains-related tax, the video discusses using a PAL and a 50/20/30 allocation.
2:50
00581
Realizing insurance as an asset engine: rebalancing × borrowing money to live by and double the growth of assets
Short
Realizing insurance as an asset engine: rebalancing × borrowing money to live by and double the growth of assets
Using a HK$250,000 policy cash value, the video compares keeping insurance with surrendering it for QQQ and QLD, then contrasts fixed rebalancing, dynamic adjustments, and PAL-funded spending.
3:17
00581
Do I still need to continue my Roth 401K when I am 57 years old? The best time and ratio to exchange VSTSX for QQQ
Short
Do I still need to continue my Roth 401K when I am 57 years old? The best time and ratio to exchange VSTSX for QQQ
A 57-year-old contributes the annual US$31,000 maximum to a Roth 401(k) with a 1.25% employer match and VTSAX as an option. The video considers reducing contributions and using a brokerage account.
1:57
00580
The market has nothing to do with me: clear out individual stocks and land, and return to QQQ asset allocation
Short
The market has nothing to do with me: clear out individual stocks and land, and return to QQQ asset allocation
After her spouse's death, a writer is managing two investment accounts, including one reportedly down more than US$150,000. She asks about stocks, land, and recent market volatility.
2:53
00580
If a Presale Home Will Not Sell, Do Not Keep Struggling: Prioritize Cash, Stop Leveraging, Default If Necessary, and Protect Your 00662/QQQ Allocation
Short
If a Presale Home Will Not Sell, Do Not Keep Struggling: Prioritize Cash, Stop Leveraging, Default If Necessary, and Protect Your 00662/QQQ Allocation
A 40-year-old single investor has about NT$47 million in 00662 and 00670L, NT$3 million in cash, and NT$5.5 million in pledged-stock debt, with NT$10 million in presale-home balances due.
2:35