00576
Simplifying asset allocation is a practice for mature investors: the transition from futures to index funds
Short
Simplifying asset allocation is a practice for mature investors: the transition from futures to index funds
A 31-year-old father has about NT$7 million, invests NT$1 million annually, and has NT$1 million each in personal and pledged loans; the video calls the portfolio too complex. All outcomes and rules are case-specific.
3:59
00576
Reverse Mortgages, Flexible Mortgages, and Retirement Allocation—Plus the Risks of Renting
Short
Reverse Mortgages, Flexible Mortgages, and Retirement Allocation—Plus the Risks of Renting
The video compares reverse mortgages with flexible mortgage facilities for retirement cash flow, continued residence, stock investing, rental issues, and fraud risk. All outcomes and rules are case-specific.
4:19
00576
From selling a house in Australia to HSBC Hong Kong: a perfect transition to tax avoidance, investment and retirement life
Short
From selling a house in Australia to HSBC Hong Kong: a perfect transition to tax avoidance, investment and retirement life
After selling an Australian home, the viewer considers reserving living costs and investing the balance through HSBC Hong Kong, asking about QQQ, NDQ, a 2% withdrawal plan, and cross-border tax reporting.
3:17
00577
If you don’t understand leverage, go back to QQQ: A mother finds a stable way to manage money amid a family crisis
Short
If you don’t understand leverage, go back to QQQ: A mother finds a stable way to manage money amid a family crisis
A 55-year-old Delaware mother recounts losses after moving from QQQ into options while managing family health and caregiving pressures. The video separates her circumstances from the speaker's long-term investing view.
5:06
00575
Cash is your last shield: understand asset allocation to survive the next stock market crash
Short
Cash is your last shield: understand asset allocation to survive the next stock market crash
A writer asks why 4-3-3 or 4-4-2 allocations still need 00865B when retirement spending uses pledged borrowing; the video treats cash as a drawdown and rebalancing buffer. All outcomes and rules are case-specific.
2:12
00575
Your medicine is not my medicine: FANG is not wrong, it’s just that your needs are different
Short
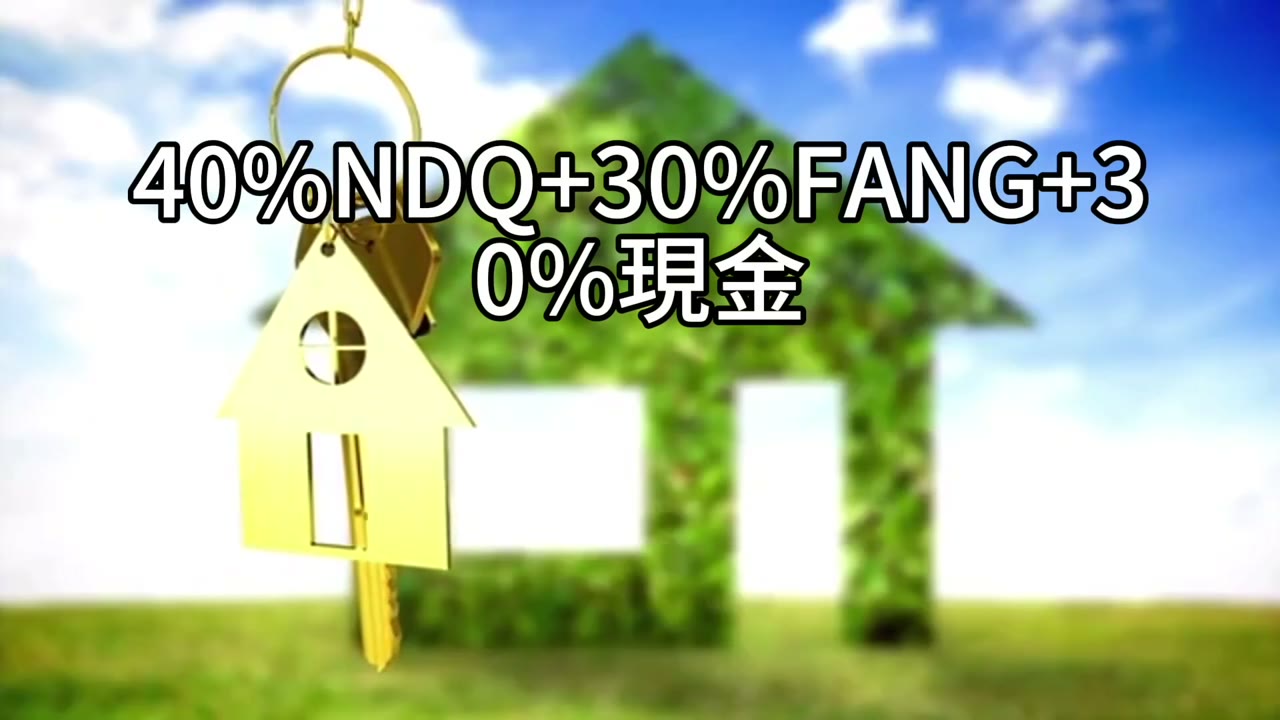
Your medicine is not my medicine: FANG is not wrong, it’s just that your needs are different
An Australian writer was given 40% NDQ, 30% FANG, and 30% cash, then saw other cases selling FANG; the video says allocations depend on cash and circumstances. All outcomes and rules are case-specific.
2:20
00575
Buying a car should not break your investment rhythm: Discuss the long-distance running mentality of assets from the choice of mortgage and car loan
Short
Buying a car should not break your investment rhythm: Discuss the long-distance running mentality of assets from the choice of mortgage and car loan
A 47-year-old with about NT$10 million invests NT$12,000 monthly in 00662 and wants a NT$600,000 family car; the video compares a car loan and pledged borrowing. All outcomes and rules are case-specific.
3:51
00575
Use a house to support yourself in old age, and you can have cash flow without selling your house: use your house to support yourself for a lifetime
Short
Use a house to support yourself in old age, and you can have cash flow without selling your house: use your house to support yourself for a lifetime
The video introduces reverse mortgages as retirement cash flow without selling a home, covering bank advances, deferred interest, and eventual estate repayment. All outcomes and rules are case-specific.
4:33
00574
VTI tax, pressure to buy a house, and dreams in my heart: million-dollar asset restart plan
Short
VTI tax, pressure to buy a house, and dreams in my heart: million-dollar asset restart plan
A 42-year-old New York healthcare worker with about US$1 million invested asks about selling VTI for QQQ, buying a Long Island school-district home within five years, and handling QLD.
9:22
00574
Children’s lucky money, mother’s credit: life restructuring from SPY to 00670L
Short
Children’s lucky money, mother’s credit: life restructuring from SPY to 00670L
A mother invested her children's gift money in SPY, now up about 50%, while the couple borrowed NT$9 million; the video compares separate child accounts with a family 4-3-3 plan. All outcomes and rules are case-specific.
4:28
00574
Borrowing as a Financial Skill: Using PAL and a HELOC to Plan Around Seven Years of Tuition and 4 Million in Assets
Short
Borrowing as a Financial Skill: Using PAL and a HELOC to Plan Around Seven Years of Tuition and 4 Million in Assets
A family with about $4.1 million plans to retire in three years and pay $50,000 of tuition annually for seven years; the video reviews PAL, HELOC, cash, and a 7.2% rate. All outcomes and rules are case-specific.
3:40
00574
Getting it right at once is a mature investment mentality: the decision to switch from QQQ to TQQQ
Short
Getting it right at once is a mature investment mentality: the decision to switch from QQQ to TQQQ
A Roth IRA is about 79% QQQ, 19% QLD, 0.3% TQQQ, and 1.2% cash, with a 60/20/10/10 target; the video favors one-step reallocation. All outcomes and rules are case-specific.
3:18