00675
The market is turbulent recently. Don’t rush into it! Survive first before you get paid: the risk control choices of a 40-year-old single mother
Short
The market is turbulent recently. Don’t rush into it! Survive first before you get paid: the risk control choices of a 40-year-old single mother
Market uncertainty frames a 40-year-old single mother earning NT$37,000 monthly, with NT$10,000 support, an NT$2 million mortgage balance, and proposals to surrender insurance, sell bonds and property, and use 70/30.
26:47
00673
60-year-old retired couple: sold the restaurant and real estate, pledged QQQI dividends + 2.5%, and only raised 3% of their 2.46 million assets with peace of mind
Short
60-year-old retired couple: sold the restaurant and real estate, pledged QQQI dividends + 2.5%, and only raised 3% of their 2.46 million assets with peace of mind
A retired California couple targets US$70,000 of annual spending from a US$2.46 million portfolio. The speaker combines 2.5% pledged borrowing with QQQI income and seeks to raise cash from 17.4% toward 30%.
7:25
00673
25 million mortgage investment technique; the five times pledge rule is disclosed; there is no need to worry about the pledge interest
Short
25 million mortgage investment technique; the five times pledge rule is disclosed; there is no need to worry about the pledge interest
A homeowner uses a flexible mortgage to release NT$25.55 million, invests through a 4-3-3 portfolio, and borrows against shares. The five-times rule and rebalancing claims do not remove leverage risk.
7:03
00672
Accompanying dad on his last journey: accepting the lesson of death, while using 30 million insurance to protect the future of mom and two granddaughters
Short
Accompanying dad on his last journey: accepting the lesson of death, while using 30 million insurance to protect the future of mom and two granddaughters
The video reviews a son’s planning as his father faces stage-four cancer: prioritizing comfort and time together, then separating the roles of roughly NT$30 million in insurance and NT$3 million in cash.
6:35
00672
Don’t work for five more years for medical insurance: 60-year-old Bay Area engineer sells 1.2 million RSUs and switches to QQQ+Roth to retire with peace of mind
Short
Don’t work for five more years for medical insurance: 60-year-old Bay Area engineer sells 1.2 million RSUs and switches to QQQ+Roth to retire with peace of mind
A Bay Area engineer nearing 60 weighs retirement with a US$2.5 million 401(k), US$1.2 million in RSUs, and US$1.3 million in cash. The speaker compares insurance, Roth conversions, concentration risk, and cash flow.
8:12
00672
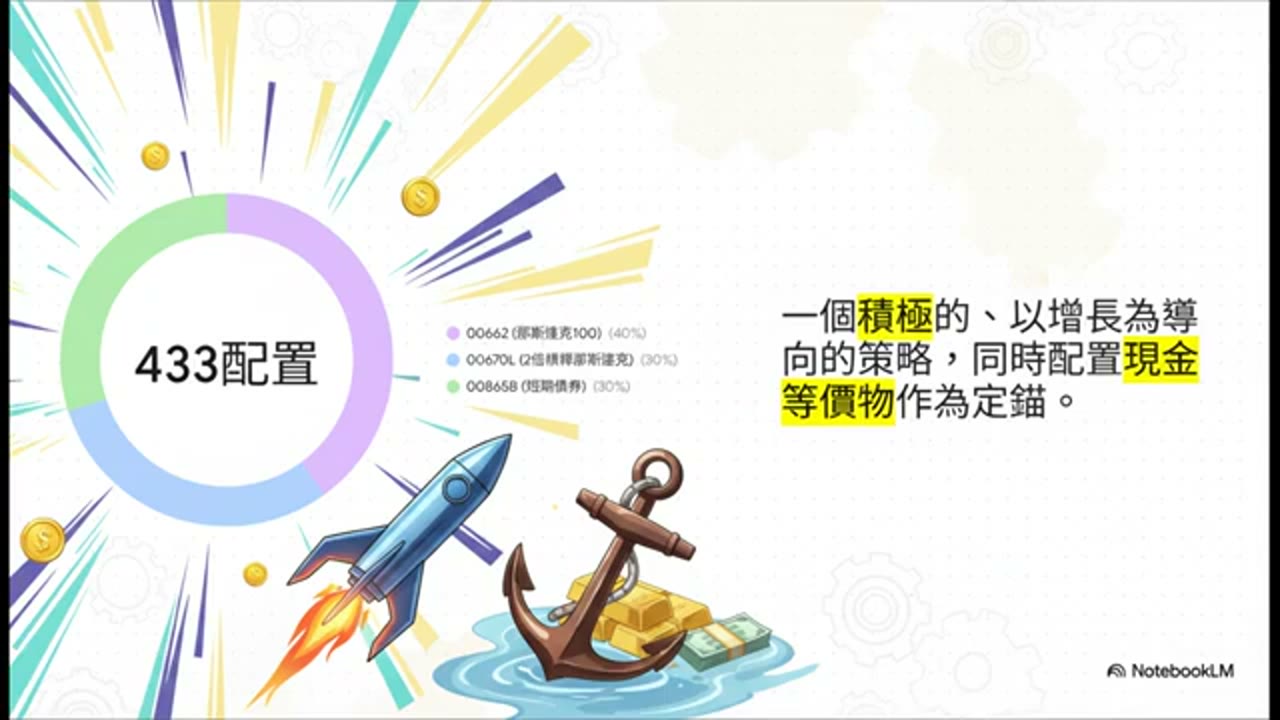
A 42-year-old couple's cash flow turned around: they sold their home, did not borrow corporate loans, and used 433+ pledges to live as capitalists
Short
A 42-year-old couple's cash flow turned around: they sold their home, did not borrow corporate loans, and used 433+ pledges to live as capitalists
A 42-year-old entrepreneurial couple weighs a business loan against selling their home. The video compares NT$2.77 million in annual expenses, a 4-3-3 portfolio, and securities-backed borrowing as a reserve.
6:15
00673
Can you retire with less than 12.5 billion? Key strategies to create cash flow with QQQI+433
Short
Can you retire with less than 12.5 billion? Key strategies to create cash flow with QQQI+433
The video reviews early retirement with NT$2.5–2.8 million in annual spending and NT$88 million in liquid assets, modeling QQQI, a 4-3-3 portfolio, and the roles of mortgage and personal debt.
13:20
00671
A 48-Year-Old Civil Servant Reworks a 20 Million Portfolio: Replace 2 Million in Savings with 433/424 and 400,000 in Annual Securities-Backed Borrowing to Practice Living off Capital
Short
A 48-Year-Old Civil Servant Reworks a 20 Million Portfolio: Replace 2 Million in Savings with 433/424 and 400,000 in Annual Securities-Backed Borrowing to Practice Living off Capital
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
7:47
00671
From Mortgage Burden to a Life of Practice: Sell a 1.5 Million Home, Withdraw 1% from 2.75 Million in Assets, and Retire in Singapore with QQQ
Short
From Mortgage Burden to a Life of Practice: Sell a 1.5 Million Home, Withdraw 1% from 2.75 Million in Assets, and Retire in Singapore with QQQ
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
5:24
00671
How to allocate your parents’ retirement cash flow? It is necessary to withdraw more than 2.5% every year and use high dividends to supplement cash
Short
How to allocate your parents’ retirement cash flow? It is necessary to withdraw more than 2.5% every year and use high dividends to supplement cash
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
9:13
00671
Live Where Life Is Convenient, Keep Your Mind Free: Choosing Between 130 Million in Redevelopment Value and a Property Trap
Short
Live Where Life Is Convenient, Keep Your Mind Free: Choosing Between 130 Million in Redevelopment Value and a Property Trap
A transcript-based review of a Taipei urban-renewal case involving rights valued at about NT$130 million, housing space versus liquidity, retirement freedom, and inheritance boundaries.
6:37
00672
Labor fights, capitalists benefit: The truth about war and Wall Street interests
Short
Labor fights, capitalists benefit: The truth about war and Wall Street interests
The speaker links workplace hierarchy and wage dependence to capital ownership, then extends the argument to oil and war finance. Claims about Iran and Wall Street are attributed, not independently verified history.
24:22