00672
From credit to retirement of 4.2 million: How to allocate assets and create retirement cash flow
Short
From credit to retirement of 4.2 million: How to allocate assets and create retirement cash flow
The video covers a civil servant managing a NT$1 million personal loan with securities-backed borrowing, and a retiree allocating a NT$4.2 million pension payout between income needs and a 70/30 portfolio.
14:11
00667
Kaohsiung single mother of four’s NT$150 million retirement plan: Use 00662+00865B+00670L to get NT$300,000 per month without selling shares
Short
Kaohsiung single mother of four’s NT$150 million retirement plan: Use 00662+00865B+00670L to get NT$300,000 per month without selling shares
A Kaohsiung single mother with four children revises a high-pressure retirement plan from a 7.2% withdrawal rate to NT$300,000 monthly spending, an NT$150 million target, and a 433 allocation.
7:18
00670
A thought can make a world of difference: Don’t be afraid if QQQ drops by 100,000. Wealth is a gift. Happiness is a human right.
Short
A thought can make a world of difference: Don’t be afraid if QQQ drops by 100,000. Wealth is a gift. Happiness is a human right.
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
6:50
00671
Only found out the tax was too high after converting Roth? Solution to retirement cash flow of 5 million assets
Short
Only found out the tax was too high after converting Roth? Solution to retirement cash flow of 5 million assets
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
16:20
00669
From asking to doing: Pledge 100,000 to test the water temperature, use QQQ+ to experience "borrowing money from your future self"
Short
From asking to doing: Pledge 100,000 to test the water temperature, use QQQ+ to experience "borrowing money from your future self"
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
7:09
00669
Taipei doesn’t need to move to Miaoli to be a caveman: a petty bourgeoisie couple with an annual salary of 2 million can use 0056 + 00662 to get out of the 18 million barista bonus in five years
Short
Taipei doesn’t need to move to Miaoli to be a caveman: a petty bourgeoisie couple with an annual salary of 2 million can use 0056 + 00662 to get out of the 18 million barista bonus in five years
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
6:21
00669
40-year-old civil servants should not be tenants: Sell 16 million apartments and invest 5 million in 00662 to have a chance to see one billion
Short
40-year-old civil servants should not be tenants: Sell 16 million apartments and invest 5 million in 00662 to have a chance to see one billion
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
7:09
00669
Retire early at the age of 50, don’t rush to pay off the mortgage: 65 million assets with 3% annual expenses, use 424 mortgage to live slowly
Short
Retire early at the age of 50, don’t rush to pay off the mortgage: 65 million assets with 3% annual expenses, use 424 mortgage to live slowly
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
7:55
00670
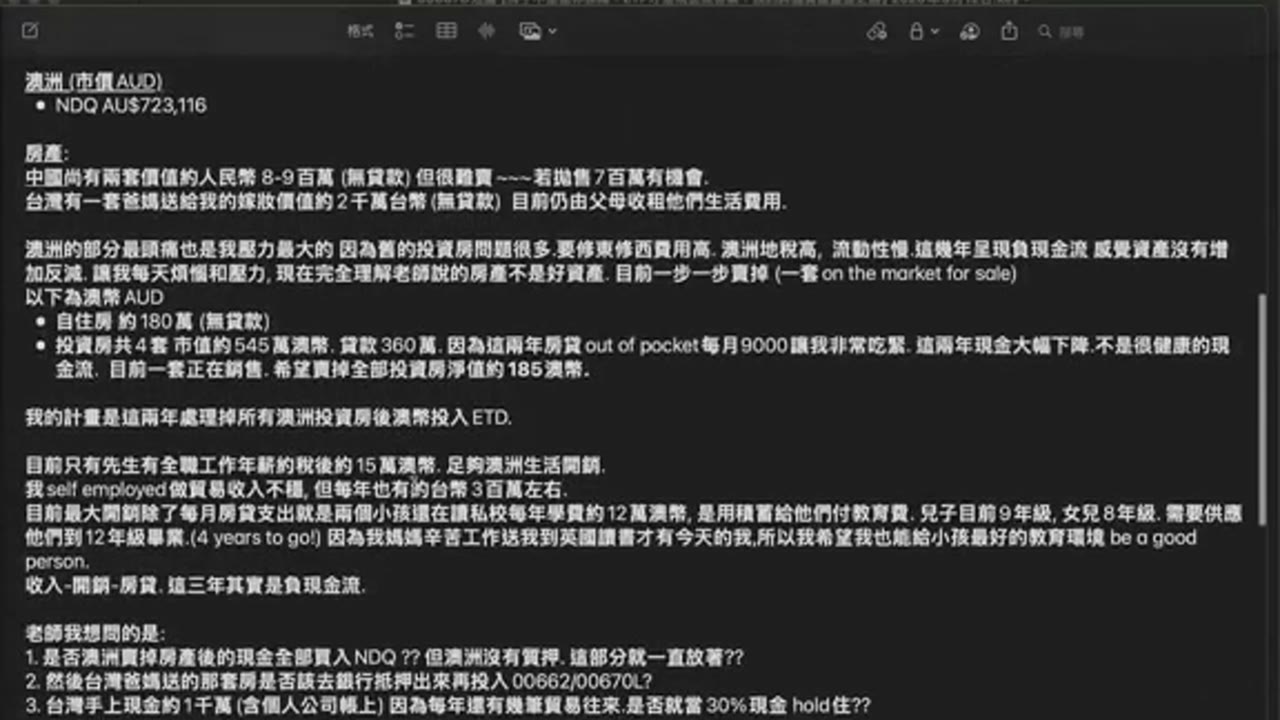
Houses are not retirement security, ETFs are the answer to cash flow: My road to cross-border asset restructuring
Short
Houses are not retirement security, ETFs are the answer to cash flow: My road to cross-border asset restructuring
A transcript-based guide to retirement cash flow, asset allocation, and borrowing decisions, separating reported facts, assumptions, trade-offs, and practical limits; figures require case-specific verification.
20:47
00668
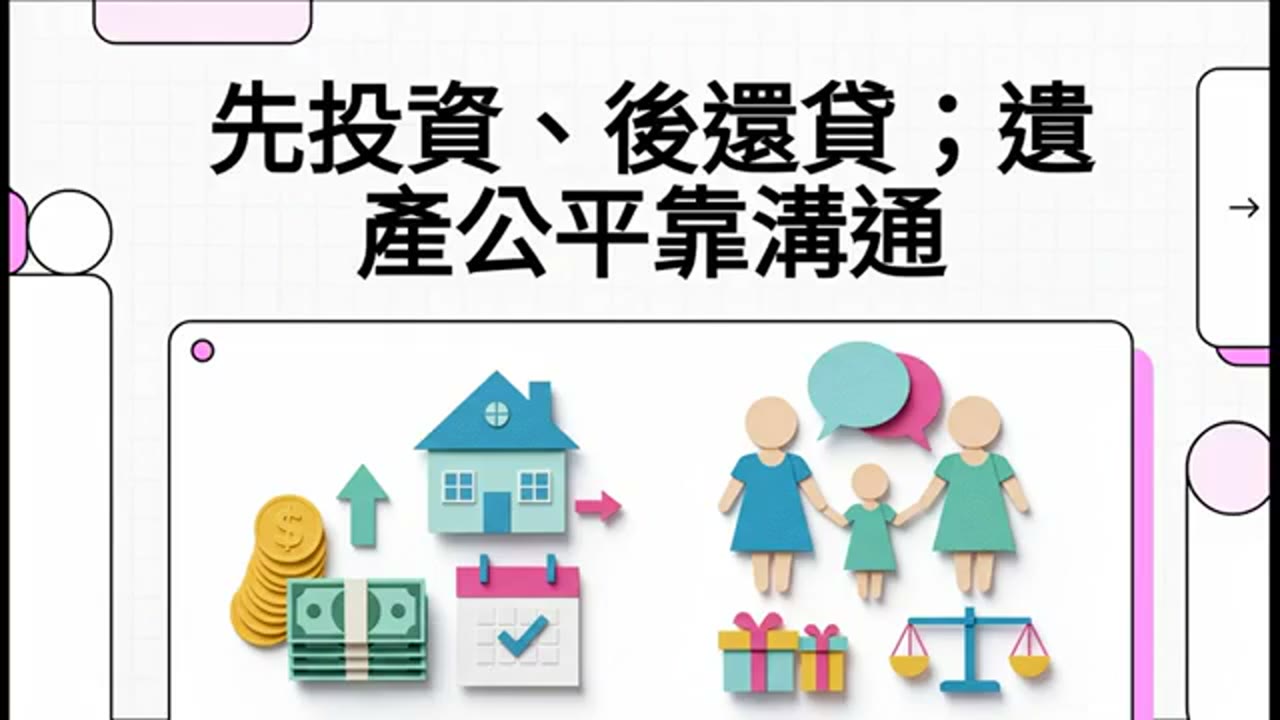
Invest first, repay later: Dare to borrow if you have a stable job for five years; inheritance for many children is fair only through communication
Short
Invest first, repay later: Dare to borrow if you have a stable job for five years; inheritance for many children is fair only through communication
The video links two decisions: borrowing NT$300,000 at 3.2% versus saving for three years, and discussing unequal inheritance support openly among multiple children.
6:24
00668
Even if you are almost 90 years old, you are not afraid of the stock market crash: QQQ+QQQI+BOXX to support your life with pension
Short
Even if you are almost 90 years old, you are not afraid of the stock market crash: QQQ+QQQI+BOXX to support your life with pension
An 86-year-old San Francisco resident with US$2 million after a home sale moves from an all-QQQ proposal to a 40% QQQ, 30% QQQI, and 30% BOXX allocation.
8:24
00668
A monthly income of US$5,000 cannot support 8% interest: Don’t pledge 300,000 US dollars, consider cash flow first and then discuss PAL
Short
A monthly income of US$5,000 cannot support 8% interest: Don’t pledge 300,000 US dollars, consider cash flow first and then discuss PAL
A 45-year-old immigrant invests US$300,000 borrowed against a home, then tests a QQQ, QQQI, and SGOV portfolio plus PAL against 8% interest, falling markets, and margin calls.
8:06