00278
Don't worry about the 1% difference in life
Short
Don't worry about the 1% difference in life
A refinancing letter compares a one-point fixed-rate difference and investing sooner, while the reply focuses on repayment terms and stable cash flow.
2:25
00277
It’s important to do the right thing in the long term
Short
It’s important to do the right thing in the long term
A letter links managing a father's money and better family communication with friends' experiences of selling, fraud, leverage, and trading losses.
4:09
00276
How do high net worth individuals prepare for estate taxes? There are hundreds of ways, but never buy insurance
Short
How do high net worth individuals prepare for estate taxes? There are hundreds of ways, but never buy insurance
A letter about insurance for estate tax leads to the speaker's views on guarantees, partial estate sales, in-kind payment, gifting, and investing.
4:40
00275
A life messed up by a house, and the government wants to share half of it with you
Short
A life messed up by a house, and the government wants to share half of it with you
A multistage retirement letter covers pensions, Social Security, health insurance, investment accounts, two aging properties, life insurance, annuity choices, taxes, and reserves.
13:50
00274
A child from a farming family can become rich by working in a factory and delivering food at night.
Short
A child from a farming family can become rich by working in a factory and delivering food at night.
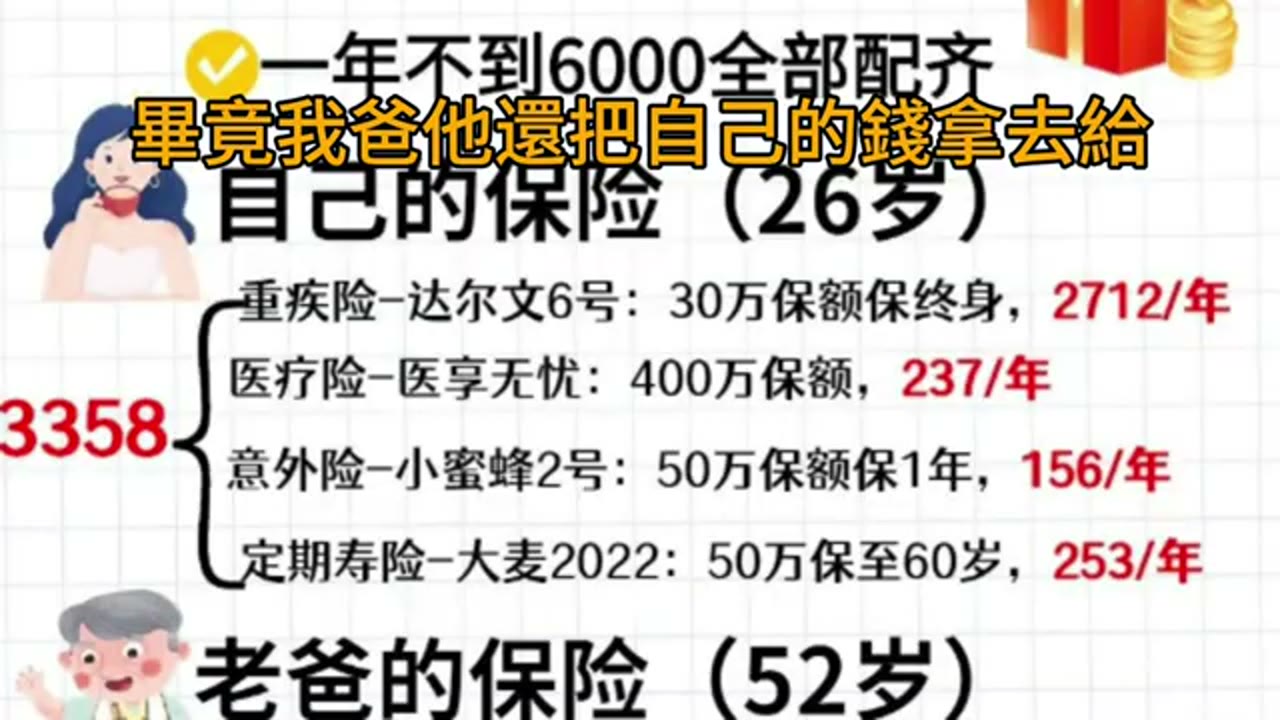
A letter connects surrendering a savings policy with family communication, recovery from fraud and debt, factory and delivery work, investing, and education.
5:22
00273
With our investment methods, you will have more money than you can ever use up
Short
With our investment methods, you will have more money than you can ever use up
A letter about taking leave after reaching a personal retirement goal leads to a discussion of enough wealth, family time, freedom, and life experience.
3:27
00488
Demand and market future: TSMC’s insights and investment trends; non-repayment of principal, growing assets and smart spending
Long
Demand and market future: TSMC’s insights and investment trends; non-repayment of principal, growing assets and smart spending
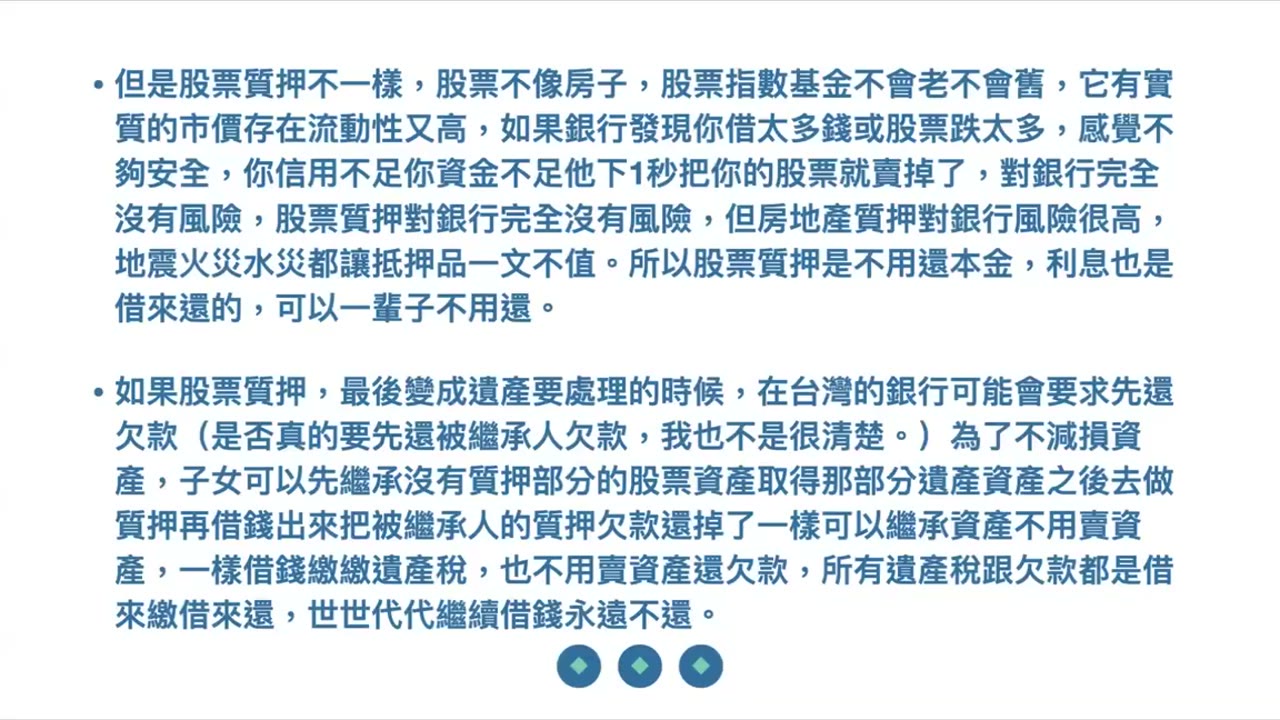
Seven sampled excerpts from a nearly three-hour discussion cover index funds, borrowing, interest rates and valuation, housing, public spending, logic, and AI. They reflect selected views and questions—not advice.
2:57:50
00272
Retail investors and amateur investors are a loser’s game! As long as you survive for a long time, you will win! No need to fight for first place
Short
Retail investors and amateur investors are a loser’s game! As long as you survive for a long time, you will win! No need to fight for first place
A discussion of market consensus and leveraged funds shifts from second-level thinking to investor behavior, emergency reserves, cash flow, and avoiding ruin.
3:39
00271
If I hadn’t bought a house and made the right investment, I should be able to retire now
Short
If I hadn’t bought a house and made the right investment, I should be able to retire now
A retirement question frames a comparison of household spending, mortgages, property, liquid investments, withdrawal rates, and two home-sale scenarios.
4:58
00270
Counter-cyclical operation, the asset allocation of the same investment target is expected to reduce volatility and increase returns, which cannot have both.
Short
Counter-cyclical operation, the asset allocation of the same investment target is expected to reduce volatility and increase returns, which cannot have both.
Through several letters, the video asks whether changing beta, leverage, and rebalancing with the market can reduce volatility while improving returns.
9:22
00269
Human beings are breaking through the limits of their own brains, and this change is a rare explosion of wealth.
Short
Human beings are breaking through the limits of their own brains, and this change is a rare explosion of wealth.
A letter imagines AI moving from computing infrastructure into production, sales, and logistics, while the speaker discusses business models and industrial change.
6:05
00268
An example of a young man learning to invest early and successfully retire early
Short
An example of a young man learning to invest early and successfully retire early
The video recalls an early learner's search for long-term investment guidance, proactive approach to learning, course participation, and interest in holding investments.
3:12