00136
Selling a house for investment is definitely a win. Letter Q&A 1
Short
Selling a house for investment is definitely a win. Letter Q&A 1
A housing-choice letter compares keeping a home with selling and renting through spending, debt, investable funds, and emergency reserves. The speaker's reply clearly favors selling and renting.
3:15
00464
[Multiple countries subtitles] The highest guiding principle of asset allocation: save taxes and build wealther
Long
[Multiple countries subtitles] The highest guiding principle of asset allocation: save taxes and build wealther
Excerpts cover market information beyond control, financial learning, long-term investing, books, local taxes and property, school costs, school choice, and child development. Speaker and participant views, not advice.
2:57:31
00135
A young man shares his investment success; spending money happily throughout his life
Short
A young man shares his investment success; spending money happily throughout his life
An annual-review letter covers market experience after an allocation change, family travel, parenting plans, and a spreadsheet on long-term investing. The speaker comments on spending, borrowing, and contributions.
7:14
00135
How can young people make the best asset allocation to achieve higher rates of return for their retirement plans?
Short
How can young people make the best asset allocation to achieve higher rates of return for their retirement plans?
A retirement-planning letter compares ideas involving housing, borrowing, cash, and an employer retirement account. The speaker then comments on account contributions, emergency reserves, and allocation codes.
5:17
00134
Fate from 26 years ago
Short
Fate from 26 years ago
A letter of thanks recalls that the writer and speaker worked at the same company without interacting, then later recognized the speaker through a video, reflecting on work, family, financial learning, and life events.
3:25
00134
As long as you are paid, you are a laborer. How do you get out of the labor dilemma?
Short
As long as you are paid, you are a laborer. How do you get out of the labor dilemma?
The video summarizes a retirement-funds comment and reply, discussing code 00662, securities-backed borrowing, cash allocation, rebalancing, and the speaker's view of retirement risk control.
2:10
00133
Returns and opportunity costs
Short
Returns and opportunity costs
The video answers a tax question about retirement-account conversion by examining opportunity cost, compounding, and why an assessment should look beyond the amount paid today.
2:45
00133
No matter what industry you are in, as long as you are paid, you are a laborer. How do you get out of the labor dilemma?
Short
No matter what industry you are in, as long as you are paid, you are a laborer. How do you get out of the labor dilemma?
A self-identified physician's letter and the speaker's reply reflect on work pressure, caregiving, retirement preparation, index-investing study, and personal views of financial independence.
4:10
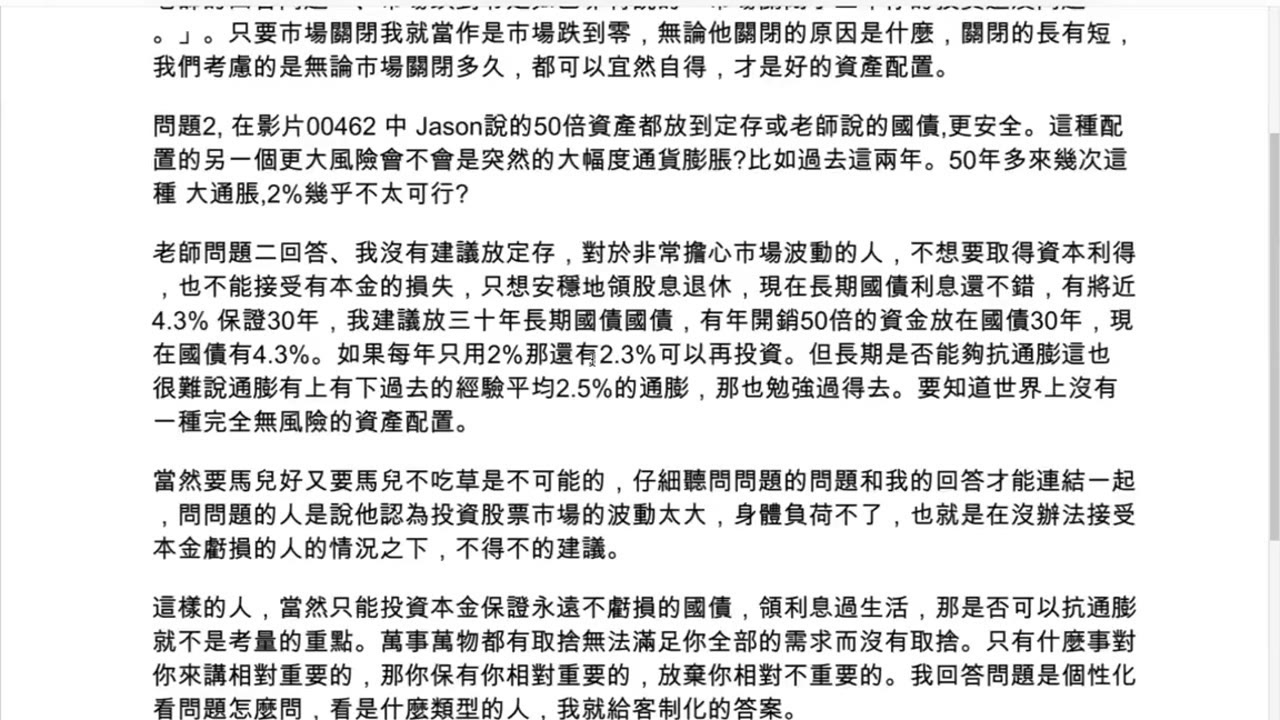
00463
[All videos have Chinese subtitles, you can turn on the subtitles] Live an optimistic life, and you will be rich if you run ahead of the IRS
Long
[All videos have Chinese subtitles, you can turn on the subtitles] Live an optimistic life, and you will be rich if you run ahead of the IRS
Excerpts cover market volatility, question context, long-term holding and trading, retirement contributions, allocation simulations, dividends, cash, and the scope of the speaker’s responses. It is not investment advice.
2:44:42
00132
[Sharing 5] The biggest difference between the rich and the poor
Short
[Sharing 5] The biggest difference between the rich and the poor
A viewer shares personal experience with buying a vehicle, stock-backed borrowing, and investing. The speaker then offers personal views on financial literacy, education, finance, and information gaps.
3:49
00132
If you don’t have a stable income and have a mortgage after retirement, how to make a safe asset allocation?
Short
If you don’t have a stable income and have a mortgage after retirement, how to make a safe asset allocation?
Using a letter about retirement and an outstanding mortgage, the video examines cash flow, emergency reserves, repayment pressure, and retirement allocation trade-offs.
2:36
00131
Sharing 4: The Rich Focus on the Big Picture; the Poor Lose Sight of What Matters
Short
Sharing 4: The Rich Focus on the Big Picture; the Poor Lose Sight of What Matters
Four viewer messages cover retirement-account conversions, taxes, medical premiums, index funds, market changes, and long-term holding. The writers' and speaker's views are personal, not site advice.
7:00