00603
High debt, low cash flow: a major reorganization of asset allocation before retirement
Short
High debt, low cash flow: a major reorganization of asset allocation before retirement
A near-retiree reports about NT$48.5 million in debt, NT$77.3 million in assets, under NT$22.3 million liquid, and more than NT$13.5 million in U.S. corporate bonds and South African rand funds.
4:00
00603
Avoid Sub-Brokerage Trading: A 27-Year-Old Civil Servant’s Investment Recovery Plan
Short
Avoid Sub-Brokerage Trading: A 27-Year-Old Civil Servant’s Investment Recovery Plan
A 27-year-old civil servant reports NT$1.8 million in low-rate loans, NT$300,000 collateral borrowing, about NT$900,000 dividend ETFs, and NT$400,000 of QQQ through sub-brokerage, plus $450 monthly.
5:51
00603
Pledge 2%: The balance between life, travel and asset growth
Short
Pledge 2%: The balance between life, travel and asset growth
A 30-year-old public employee earning about NT$1 million reports NT$6.5 million invested in 60% 00662, 10% 00670L, and 30% 00865B, plus several loans, and asks about borrowing 2% yearly.
4:28
00603
The core of retirement asset allocation: understand cash flow first, then talk about capital appreciation
Short
The core of retirement asset allocation: understand cash flow first, then talk about capital appreciation
A 63-year-old reports about NT$7 million in dividend stocks, NT$1 million in foreign bond funds, NT$10 million in deposits, NT$3 million policy value, and NT$35,000 monthly pension income.
4:18
00543
What to do when the market is fearful? Market fear and the mentality of getting rich in the real estate cage
Long
What to do when the market is fearful? Market fear and the mentality of getting rich in the real estate cage
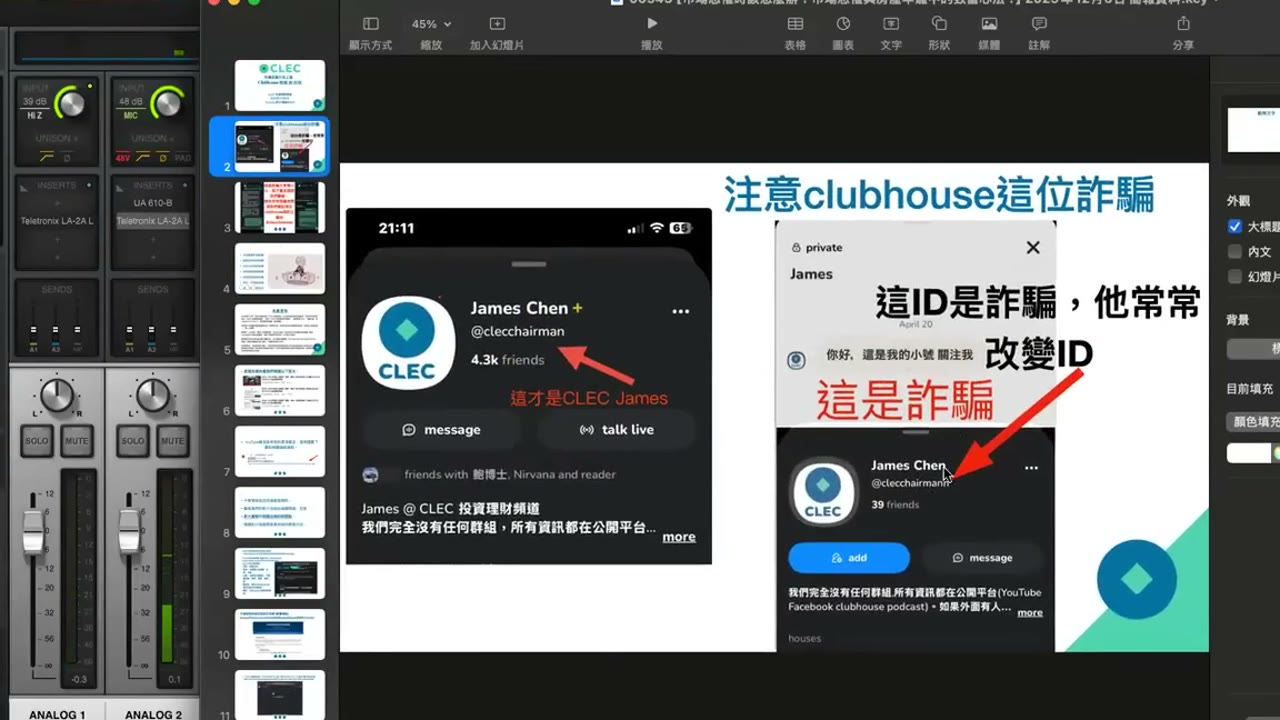
The video covers impersonation scams, market fear, index-fund and cash questions, a child's creative path, health changes, stock-picking and home-loan stress, QQQI withholding claims, and asset-backed borrowing.
2:01:37
00602
A Seven-Year Retirement Blueprint: Balancing Asset Allocation and Cash Flow
Short
A Seven-Year Retirement Blueprint: Balancing Asset Allocation and Cash Flow
An investor planning retirement in seven years reports about NT$16.8 million in a 6:1:3 allocation, NT$8 million in Taiwan ETFs, roughly NT$160,000 monthly contributions, and NT$2 million reserves.
4:47
00602
Stay away from the media noise and return to your original intention of investing
Short
Stay away from the media noise and return to your original intention of investing
A mainland China investor moved from individual stocks to long-term Nasdaq-100 investing but remains anxious about political news. The speaker favors less news exposure; claims of inevitable progress are opinions.
3:45
00602
In Your 50s in Hong Kong: Grow with the Nasdaq-100 and Fund Cash Flow with High-Dividend and Currency ETFs
Short
In Your 50s in Hong Kong: Grow with the Nasdaq-100 and Fund Cash Flow with High-Dividend and Currency ETFs
A Hong Kong reader in her fifties wants liquid assets to support both long-term growth and living cash flow after a difficult marriage. The video proposes a Nasdaq core plus money-market or dividend ETFs.
6:15
00602
Investing in Hong Kong: Balancing Cash Flow and Growth with High-Dividend ETFs vs. the Nasdaq-100
Short
Investing in Hong Kong: Balancing Cash Flow and Growth with High-Dividend ETFs vs. the Nasdaq-100
The video compares Hong Kong Nasdaq-100, high-dividend, and money-market ETFs, naming 3086, 9086, 2834, 9834, 3110, 3190, 3070, 2800, and 3096/9096 with stated yields.
3:24
00601
First stabilize the cash flow of 740,000, and then let the assets grow: 0056 of 12 million plus 613 asset allocation
Short
First stabilize the cash flow of 740,000, and then let the assets grow: 0056 of 12 million plus 613 asset allocation
A 53-year-old mother caring for her 27-year-old autistic child reports NT$29 million in assets, NT$1.1 million annual spending, and NT$360,000 salary. The video models NT$12 million in 0056, a 6:1:3 mix, and a trust.
6:11
00601
Sell a Home for Cash Flow, Make QQQ the Core: Accelerating Growth with Securities-Backed Lending and Roth
Short
Sell a Home for Cash Flow, Make QQQ the Core: Accelerating Growth with Securities-Backed Lending and Roth
A self-employed single investor has sold three rentals and reports about $590,000 net from the latest sale, reserving $140,000 for tax and $100,000 for renovation while weighing BOX, investing, or PAL repayment.
5:24
00601
Wealth is a gift: exchange a room for an asset that will grow
Short
Wealth is a gift: exchange a room for an asset that will grow
A Canadian viewer plans to sell a rental when its mortgage matures, fund retirement accounts, and invest about C$260,000 remaining in HXQ. A 15-year model claims a nearly ninefold gap, but returns are not guaranteed.
3:07