00034
Investment Philosophy and Asset Allocation for Financial Freedom (English Audio)
Topics
Investment Philosophy and Asset Allocation for Financial Freedom (English Audio)
The video presents the speaker's views on a long-term investing mindset, asset allocation, leveraged rebalancing, retirement cash flow, and the relationship between financial choices and personal freedom.
9:19
00593
Bad choices make you poorer: Cash flow is the key
Short
Bad choices make you poorer: Cash flow is the key
A Taipei household has a mortgage around 2.35%–2.86%, debt from failed investing, and a monthly deficit, and considers refinancing for more cash. The speaker argues for expense cuts and savings before new borrowing.
3:03
00593
Make good use of legal tools and financial planning to protect your property and family
Short
Make good use of legal tools and financial planning to protect your property and family
A viewer shares Taiwan experience with assistance declarations, guardianship, and a care trust for relatives with cognitive decline. Legal authority, investment limits, and bank procedures require case review.
3:33
00593
Don’t linger on the wrong asset: switching now is the right choice
Short
Don’t linger on the wrong asset: switching now is the right choice
Using a viewer's 00631L and 00933B holdings, the speaker calls for an immediate sale and a shift to 40% 00662, 30% 00670L, and 30% 00865B. The product judgments and timing are program opinions.
3:03
00593
Brothers and sisters learn to invest together: Family consensus brings a happy life
Short
Brothers and sisters learn to invest together: Family consensus brings a happy life
The viewer's brother plans to sell two Taipei properties for about NT$70 million, retain a suburban home, and keep NT$3 million in reserves alongside NT$500,000 annual transfer income. The speaker proposes 70:30.
2:59
00541
Double leverage will not return to zero, but it will fall to the point where you doubt your life: without rebalancing, no one can save you.
Long
Double leverage will not return to zero, but it will fall to the point where you doubt your life: without rebalancing, no one can save you.
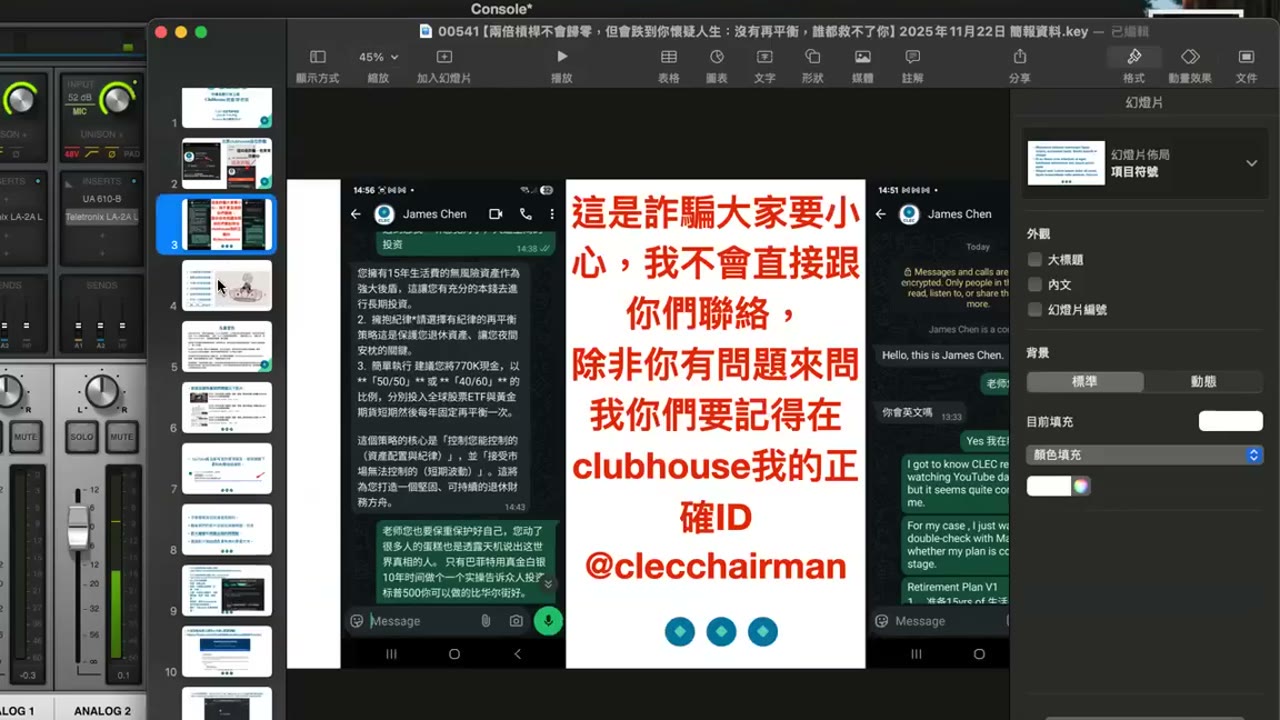
The video discusses market volatility and rebalancing, leverage and borrowing, long-term funds for children, support networks, diverse schools, multilingual video distribution, and AI-enabled impersonation scams.
2:48:53
00592
Don’t be led away by the commissioner: Correct allocation is more stable than bonds
Short
Don’t be led away by the commissioner: Correct allocation is more stable than bonds
Josh asks about his roughly 65-year-old mother's NT$500,000 investment-linked policy and NT$1.8 million bond proposal. The speaker rejects both and proposes 70% 00662 and 30% 00865B, subject to product review.
3:24
00592
Accumulating 60 million in 10 years: the power of asset allocation and disciplined investment
Short
Accumulating 60 million in 10 years: the power of asset allocation and disciplined investment
A couple reports about NT$22.7 million in investments and NT$2 million in annual spending, targeting NT$60 million in ten years. The speaker proposes monthly additions, a 5:1:4 allocation, and annual borrowing.
3:08
00592
Declaration of overseas assets: Only by filing taxes legally can you repatriate with peace of mind
Short
Declaration of overseas assets: Only by filing taxes legally can you repatriate with peace of mind
A Taiwan viewer holds $2 million in Singapore after a Shanghai property sale and considers 70% QQQ and 30% money market. The video cites foreign-income reporting and an NT$7.5 million threshold requiring tax review.
3:33
00592
When to receive Social Security benefits: early or late? Numbers tell you the answer
Short
When to receive Social Security benefits: early or late? Numbers tell you the answer
The video compares Social Security at 62 for $872 monthly with a $2,363 spousal amount at 67, assuming both are invested in QQQ at 14% through age 90. Eligibility, longevity, and returns are conditional.
3:20
00591
Mirror Self: The Path to Wealth and Happiness That Starts with Affirmation
Short
Mirror Self: The Path to Wealth and Happiness That Starts with Affirmation
Responding to a student preparing for a new life in the United States, the video connects affirmation, communication, and personal choice with a long-term QQQ approach that avoids reacting to short-term volatility.
2:20
00591
The wisdom of cash allocation: the dual balance of account distribution and tax savings
Short
The wisdom of cash allocation: the dual balance of account distribution and tax savings
The video asks whether cash belongs in a PAL or retirement account and applies the speaker's 30% aggregate-cash rule. It then uses an annual US$430,000 IRA-to-Roth conversion as a tax example.
3:17