00686
Fight to death and never sell, live forever: the evolutionary path from leverage to cycle
Short
Fight to death and never sell, live forever: the evolutionary path from leverage to cycle
The video argues that long-term holding first requires remaining able to stay invested, covering QQQI return-of-capital tax effects, spending wealth during life, and cycle-based defense.
27:13
00685
How long will the US-Iraq war continue? Controlling oil = controlling the world: the ultimate logic of US dollar hegemony
Short
How long will the US-Iraq war continue? Controlling oil = controlling the world: the ultimate logic of US dollar hegemony
The speaker offers a personal theory connecting the U.S.–Iran war, oil trade, and dollar power. The claimed motives and timeline are geopolitical inferences, not independently verified facts.
17:58
00685
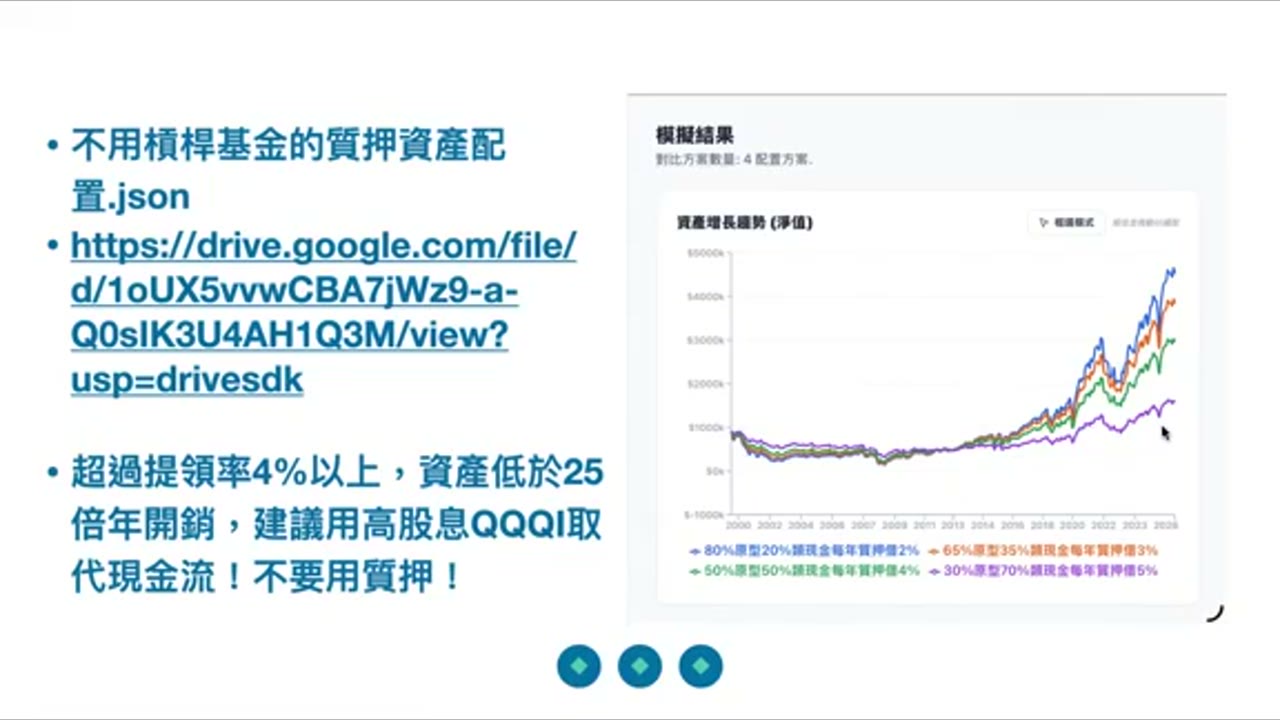
Don’t use leverage to make pledges, and don’t use pledges for assets below the amount: the simplest solution to retirement cash flow
Short
Don’t use leverage to make pledges, and don’t use pledges for assets below the amount: the simplest solution to retirement cash flow
The speaker argues that withdrawal rates above 4%, or assets below roughly 25 times annual spending, may be poorly suited to securities-backed borrowing for retirement cash flow.
19:47
00559
The nature of U.S. dollar hegemony; insufficient pension, how to obtain stable cash flow for retirement
Long
The nature of U.S. dollar hegemony; insufficient pension, how to obtain stable cash flow for retirement
The video discusses sustainable asset allocation, LLMs and identity, cycle-based methods, the context needed for retirement planning, emergency liquidity, and the difference between strategy and short-term action.
1:50:49
00684
Stop borrowing money to live! First make the cash flow positive: fund redemption + 00662 long-term buying
Short
Stop borrowing money to live! First make the cash flow positive: fund redemption + 00662 long-term buying
A family earning NT$110,000 monthly has used nearly NT$2.5 million of a 2.9% home-equity credit line. The video argues for ending debt-funded investing and restoring positive cash flow.
8:08
00683
Response to market fluctuations: Cash is a shock absorber, discipline is a moat
Short
Response to market fluctuations: Cash is a shock absorber, discipline is a moat
The video discusses cash and position sizing after a market rebound through a case involving Hong Kong funds, mainland index products, rental properties, and a planned home sale.
21:19
00683
Retire first! Life and body are more important than money: tracking 0.8 cm nodules + how to allocate retirement cash flow
Short
Retire first! Life and body are more important than money: tracking 0.8 cm nodules + how to allocate retirement cash flow
A 48-year-old single mother considers retirement after a roughly 0.8 cm lung nodule is found while supporting two children and her 75-year-old mother. The speaker prioritizes health and simplifies cash flow.
9:22
00683
Be yourself and get back to your roots: On marriage, childbirth and life control
Short
Be yourself and get back to your roots: On marriage, childbirth and life control
Marriage, parenthood, divorce, and everyday compromise are framed as choices rather than a mandatory life script. The three-part model separates personal values from social expectations.
6:52
00683
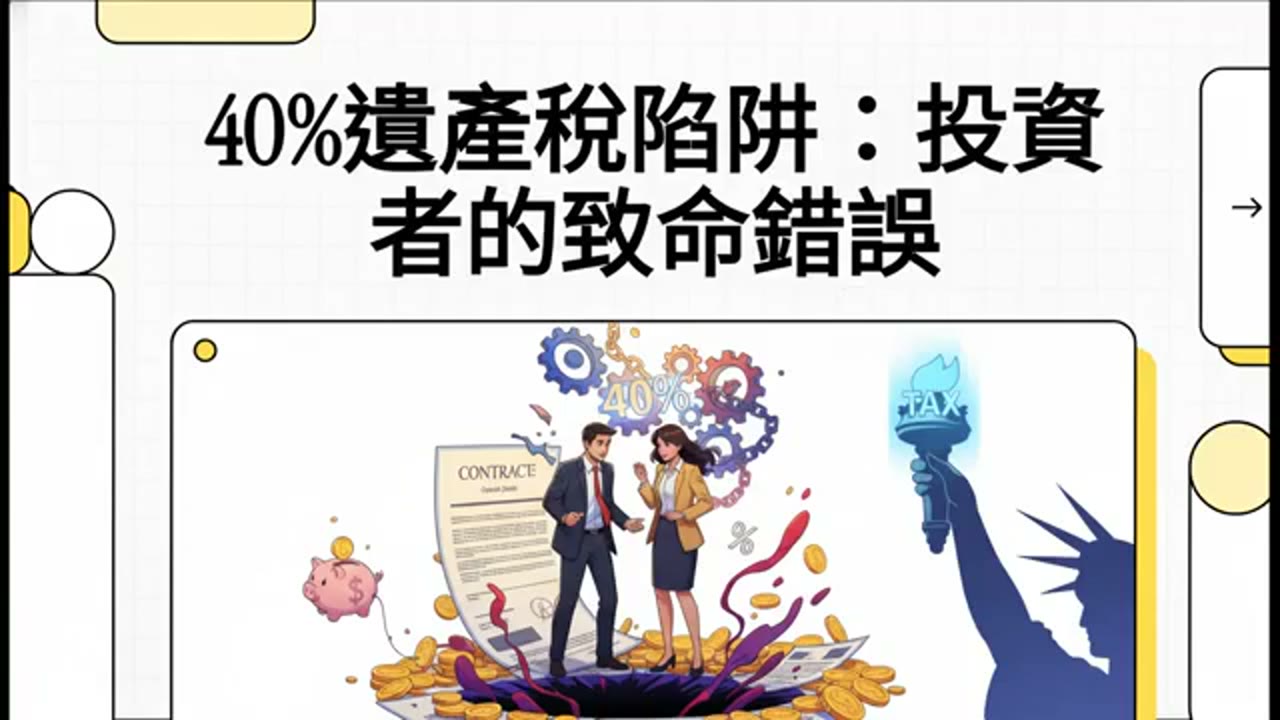
Save Tax in Your Mother’s Name? The Hidden 40% Estate-Tax Trap Behind Financial-Industry Advice
Short
Save Tax in Your Mother’s Name? The Hidden 40% Estate-Tax Trap Behind Financial-Industry Advice
Using a non-US parent’s name for an investment account may replace capital-gains planning with estate-tax and inheritance risk. The stated US$60,000 exemption and 40% rate require current verification.
7:30
00682
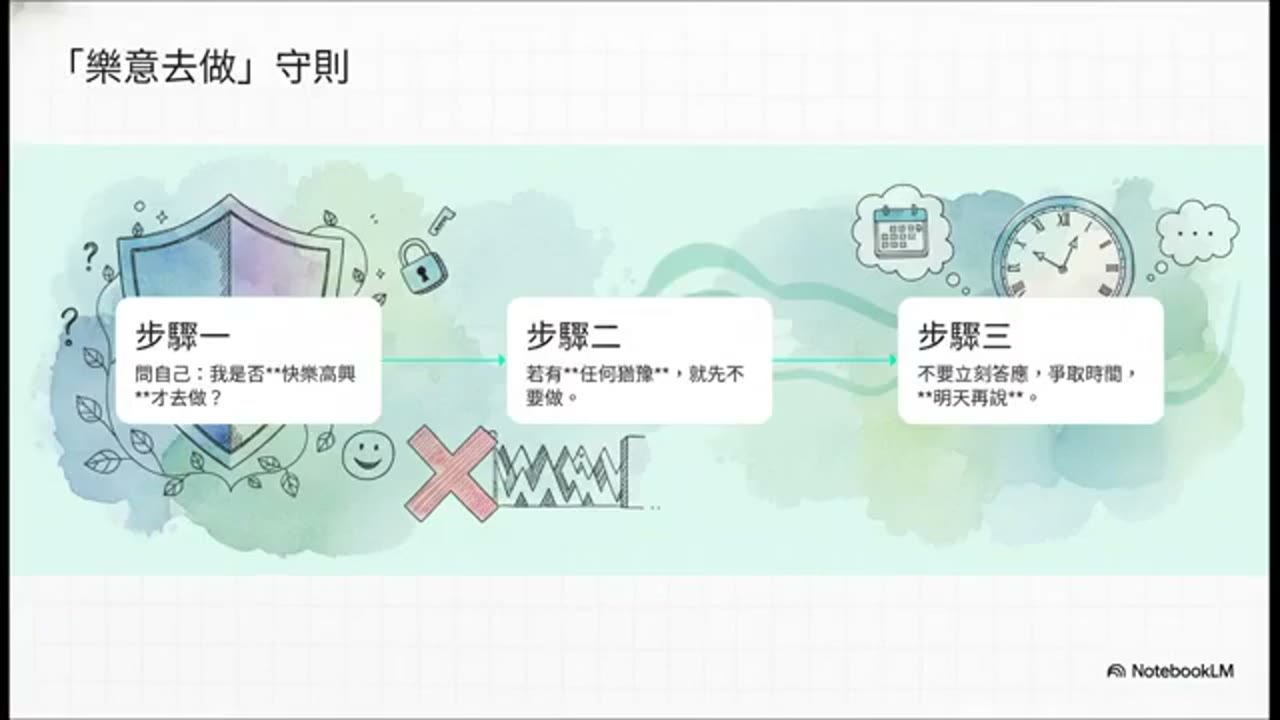
Think about yourself first, you can regret it even if you don’t like it: learn the courage to say no in the workplace
Short
Think about yourself first, you can regret it even if you don’t like it: learn the courage to say no in the workplace
A long-tenured manager reluctantly accepts an unexpected team transfer, then calls back to decline. The speaker’s boundary framework checks willingness, pauses when unsure, and asks for decision time.
5:06
00682
55-year-old single mother in the financial industry: From anxiety to 100 million in 4 years, the last hurdle is retirement
Short
55-year-old single mother in the financial industry: From anxiety to 100 million in 4 years, the last hurdle is retirement
A 55-year-old single mother in finance reports changing her approach in 2021 and reaching NT$100 million four years later using Nasdaq funds, reserves, leverage, and pledged credit. The result does not prove causation.
7:14
00682
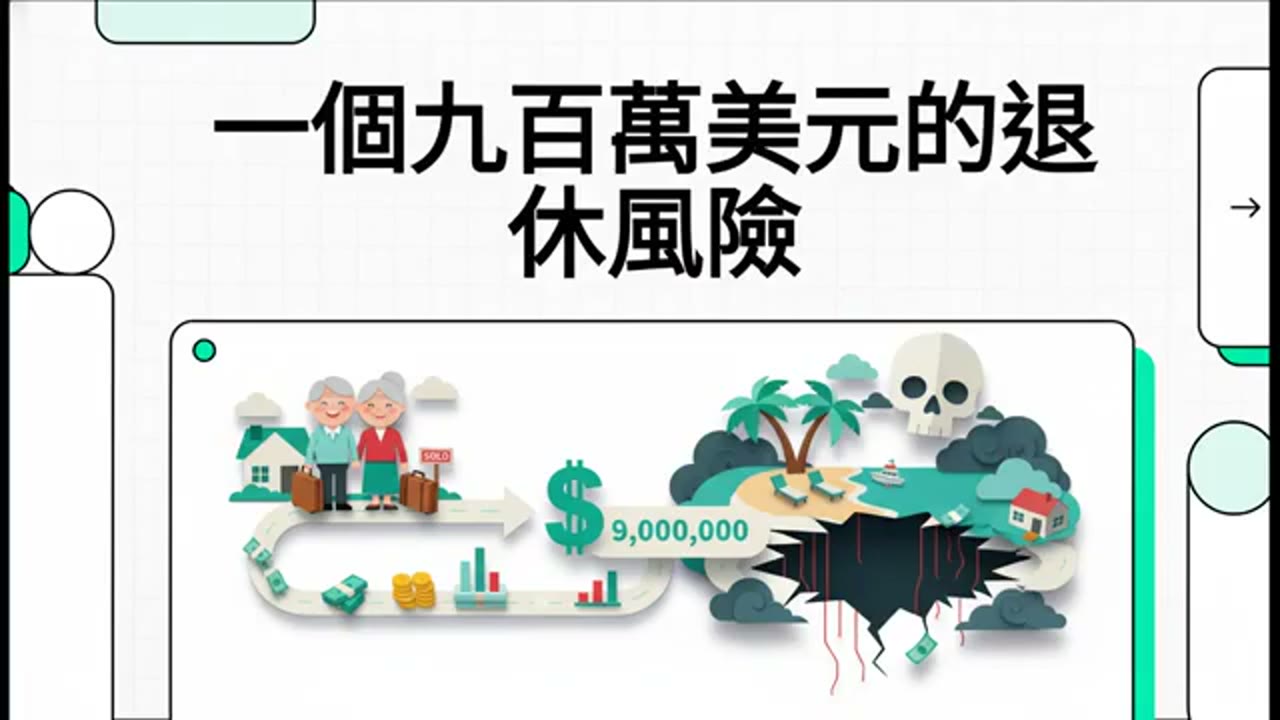
Vacation Home Sold! You have too little cash: if the market drops 85%, you may go bankrupt
Short
Vacation Home Sold! You have too little cash: if the market drops 85%, you may go bankrupt
A stress test examines US$9.2 million with 98% Nasdaq exposure, about 1% cash-like assets, and a US$700,000 pledged loan. The speaker uses an 85% decline scenario and targets 30% liquidity.
10:49