00676
A Couple at 60 with 30 Million in Assets: Use 20% QQQI for Cash Flow and 80% for Growth—No Need to Wait Five Years
Short
A Couple at 60 with 30 Million in Assets: Use 20% QQQI for Cash Flow and 80% for Growth—No Need to Wait Five Years
A 60-year-old couple with NT$30 million and NT$1.2 million annual spending considers retiring now through 20% QQQI cash flow and 2.5% withdrawals from an 80% core portfolio.
6:51
00557
Clubhouse [0190] YT (00557) broadcasts a relaxed chat about investment; investment secrets; keys to getting rich; the first step to start investing
Long
Clubhouse [0190] YT (00557) broadcasts a relaxed chat about investment; investment secrets; keys to getting rich; the first step to start investing
This investment Q&A covers earlier course material, industry enthusiasm and capital spending, moving averages, income planning, career choices, and questions about a volatile holding.
3:18:12
00557
The market will drop 80%, can you still hold on? The key is asset allocation
Long
The market will drop 80%, can you still hold on? The key is asset allocation
The video moves from cash levels during instability to business-cycle reading, then uses moving averages, a neckline, and rebound patterns to explain the speaker's view of bearish signals, resistance, and trend changes.
27:27
00676
The stock market is a killing battlefield, so don’t be careful! Understand the cycle, remember to bring an umbrella, and stay alive!; If you are afraid of the market falling, you should not invest.
Short
The stock market is a killing battlefield, so don’t be careful! Understand the cycle, remember to bring an umbrella, and stay alive!; If you are afraid of the market falling, you should not invest.
The speaker discusses cycles, cash, and beta, then reviews a 44-year-old household with RMB 5 million, no employment income, and RMB 300,000 annual spending. He admits the cycle call may be wrong.
35:40
00675
Don’t use stocks as collateral to borrow 5 million at a time! Change to borrow from CITIC: 5 million redo 433 + pledge and only borrow 2% per year to repay the credit
Short
Don’t use stocks as collateral to borrow 5 million at a time! Change to borrow from CITIC: 5 million redo 433 + pledge and only borrow 2% per year to repay the credit
A nearly NT$40 million portfolio with over 80% in growth and leveraged holdings compares a one-time NT$5 million PAL draw with personal credit and a 433 rebalance.
5:36
00675
A 60-year-old professor's "Fear to Awakening": 3.1 million in traditional retirement accounts, 400,000 in Roth conversions every year for 15 years, allowing assets to grow in tax-free accounts
Short
A 60-year-old professor's "Fear to Awakening": 3.1 million in traditional retirement accounts, 400,000 in Roth conversions every year for 15 years, allowing assets to grow in tax-free accounts
A 60-year-old U.S. professor with US$2.4 million in a 403(b) and US$700,000 in a 457(b) considers 15 years of roughly US$400,000 annual Roth conversions and asset location.
9:16
00675
New immigrant with assets of 2 million US dollars: first use QQQI to lock in 100,000 years of cash flow, and then pledge his life back to QQQ
Short
New immigrant with assets of 2 million US dollars: first use QQQI to lock in 100,000 years of cash flow, and then pledge his life back to QQQ
A 42-year-old physician newly in the U.S. has US$2 million but insufficient income, leading to an US$850,000 QQQI cash-flow model and a 70% QQQ, 30% BOXX allocation.
7:16
00675
The easiest way for a 28-year-old novice to build wealth: No need to allocate assets, just keep buying Nasdaq ETFs
Short
The easiest way for a 28-year-old novice to build wealth: No need to allocate assets, just keep buying Nasdaq ETFs
A 28-year-old bank IT worker with mortgage and personal-loan anxiety returns to Nasdaq-100 investing after selling out five years earlier and watching the index roughly double.
6:57
00675
The market is turbulent recently. Don’t rush into it! Survive first before you get paid: the risk control choices of a 40-year-old single mother
Short
The market is turbulent recently. Don’t rush into it! Survive first before you get paid: the risk control choices of a 40-year-old single mother
Market uncertainty frames a 40-year-old single mother earning NT$37,000 monthly, with NT$10,000 support, an NT$2 million mortgage balance, and proposals to surrender insurance, sell bonds and property, and use 70/30.
26:47
00674
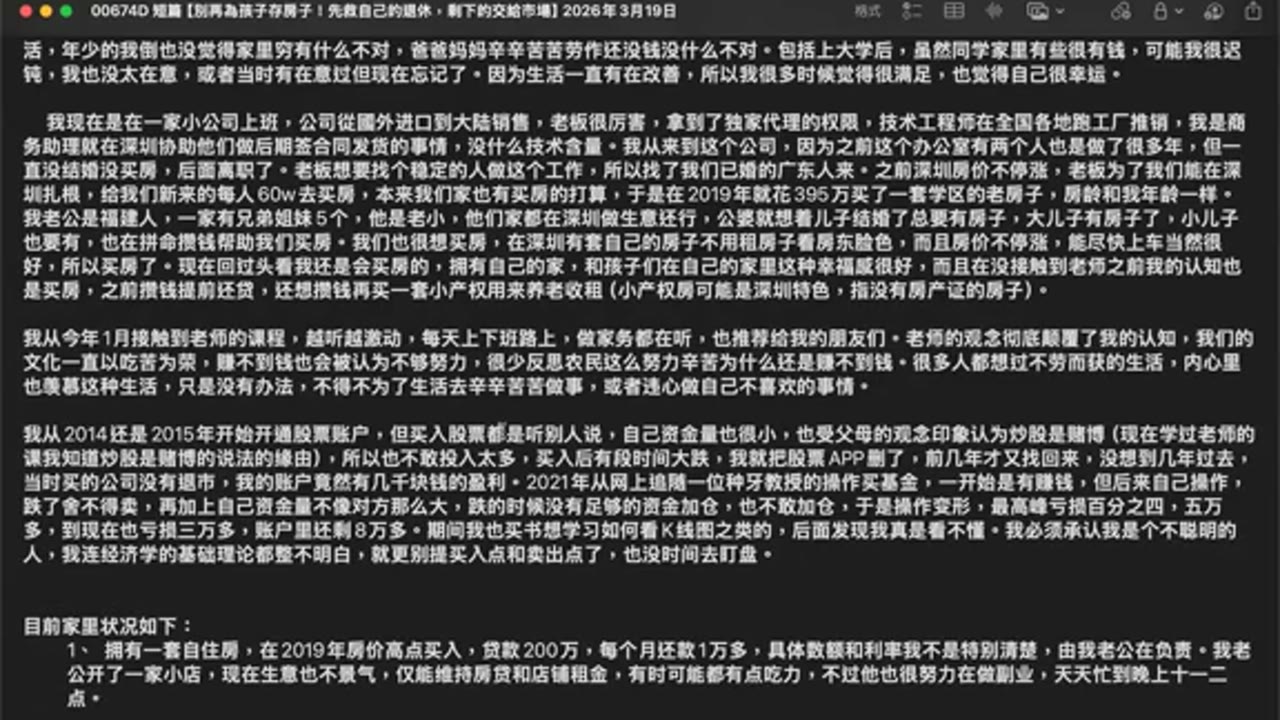
Stop saving a house for your kids! Save yourself for retirement first, and leave the rest to the market
Short
Stop saving a house for your kids! Save yourself for retirement first, and leave the rest to the market
A Shenzhen family weighs retirement, housing for two children, parental medical duties, losing funds, annual Nasdaq-100 investing, a 70/30 allocation, and a one-year reserve.
36:31
00674
Stage four lung cancer comes too soon: cash flow is the lifeline for the family
Short
Stage four lung cancer comes too soon: cash flow is the lifeline for the family
A family facing a 76-year-old mother’s stage IV lung cancer lists NT$4,500 daily room fees, NT$100,000 monthly lodging, and NT$180,000 to NT$260,000 treatment costs.
5:24
00674
Sell investment house + stop insurance: 44-year-old Southern California mother uses 600,000 to restart QQQ life
Short
Sell investment house + stop insurance: 44-year-old Southern California mother uses 600,000 to restart QQQ life
A 44-year-old Southern California mother reviews U.S. and China property, insurance, stocks, and retirement accounts after RMB600,000 of premiums leave about RMB400,000 of cash value.
8:40