
00048
Retirement Withdrawals and QQQ Beyond Tech Stocks: Selling a Home and Going All In on QQQ vs. the Belief That Property Creates Wealth (English Audio)
Topics
Retirement Withdrawals and QQQ Beyond Tech Stocks: Selling a Home and Going All In on QQQ vs. the Belief That Property Creates Wealth (English Audio)
The video asks whether QQQ should be viewed as a concentrated technology holding, then presents the speaker's views on long-term investing, a 2.5% retirement withdrawal threshold, and property versus liquid investments.
7:23

00047
How to Use the Asset-Allocation Backtesting Software
Topics
How to Use the Asset-Allocation Backtesting Software
A practical walkthrough of the updated asset allocation backtesting tool, covering portfolio creation and duplication, rebalancing comparisons, result exports, cash-flow views, and household balance sheets.
28:56
00620
Asset allocation reduced from 433 to 514 Beta: Withdraw 3% every year, travel around the world with peace of mind
Short
Asset allocation reduced from 433 to 514 Beta: Withdraw 3% every year, travel around the world with peace of mind
A 53-year-old civil servant reports NT$82 million in stocks, a NT$45 million flexible mortgage costing NT$1.08 million yearly, and NT$2.6 million household spending. The video compares retirement options.
10:03
00619
Allocating in proportion is the real disciplined investment
Short
Allocating in proportion is the real disciplined investment
The viewer contributes NT$30,000 monthly to 00662 and holds roughly 50% 00662, 25% 00670L, and 25% 00865B, asking whether a new NT$200,000 loan should go to one fund or follow the allocation.
2:34
00619
Selling your house to retire? Asset allocation is key
Short
Selling your house to retire? Asset allocation is key
A 58-year-old in Australia expects A$1.3 million from selling two investment properties and about A$1.5 million total. The video tests retirement at A$50,000 yearly spending and proposes 70% NDQ with 30% cash.
3:26
00619
Live on borrowed money, invest your salary: the wise choice of the bourgeoisie
Short
Live on borrowed money, invest your salary: the wise choice of the bourgeoisie
The viewer asks whether a US$50,000 PAL loan at 7.51% costs about US$3,755 yearly and how Fed cuts, short-duration cash holdings, and salary affect borrowing costs and payments.
3:42
00619
Buying a House vs. Renting: Two Lives Thirty Years Later
Short
Buying a House vs. Renting: Two Lives Thirty Years Later
A married 27-year-old lives with her husband’s family while her mother and sister rent. A prior jointly funded home sale left about NT$5 million. The video compares buying for her mother, renting, and index investing.
3:21
00618
Defuse the Bomb First: Excessive Collateral Is a Bankruptcy Risk, Not an Allocation Issue
Short
Defuse the Bomb First: Excessive Collateral Is a Bankruptcy Risk, Not an Allocation Issue
A 30-year-old earning NT$50,000 monthly reports NT$1.2 million of stock-backed borrowing, a NT$450,000 personal loan, and about NT$1.7 million available. The video prioritizes margin-call risk before 4:3:3.
6:39
00618
Should interest payments fill the gap, or should growth come first? ——A letter from 66 million retirement assets
Short
Should interest payments fill the gap, or should growth come first? ——A letter from 66 million retirement assets
A retired household reports NT$66 million: about NT$15.5 million in dividend ETFs, NT$37.3 million in 00662, and NT$13.1 million in cash and other assets. The video reviews a NT$1–1.2 million annual gap.
4:37
00618
Cash is your safety cushion
Short
Cash is your safety cushion
Even with stable pensions and reverse-mortgage payments, the video opposes cutting cash reserves. Medical, vehicle, and family emergencies support a framework of one year’s spending or 30% of assets in cash.
2:28
00618
Renewal Risk in Flexible Mortgages: A Hidden Threat to Retirement Cash Flow
Short
Renewal Risk in Flexible Mortgages: A Hidden Threat to Retirement Cash Flow
Two NT$12 million loans use a 30-year amortizing mortgage at 2.29% and a seven-year flexible mortgage at 2.59%. The video compares payments, pledged-asset funding, renewal, and balloon risk.
3:12
00046
Updated Asset-Allocation and Securities-Backed Borrowing Software: A 2000–2025 Backtest
Topics
Updated Asset-Allocation and Securities-Backed Borrowing Software: A 2000–2025 Backtest
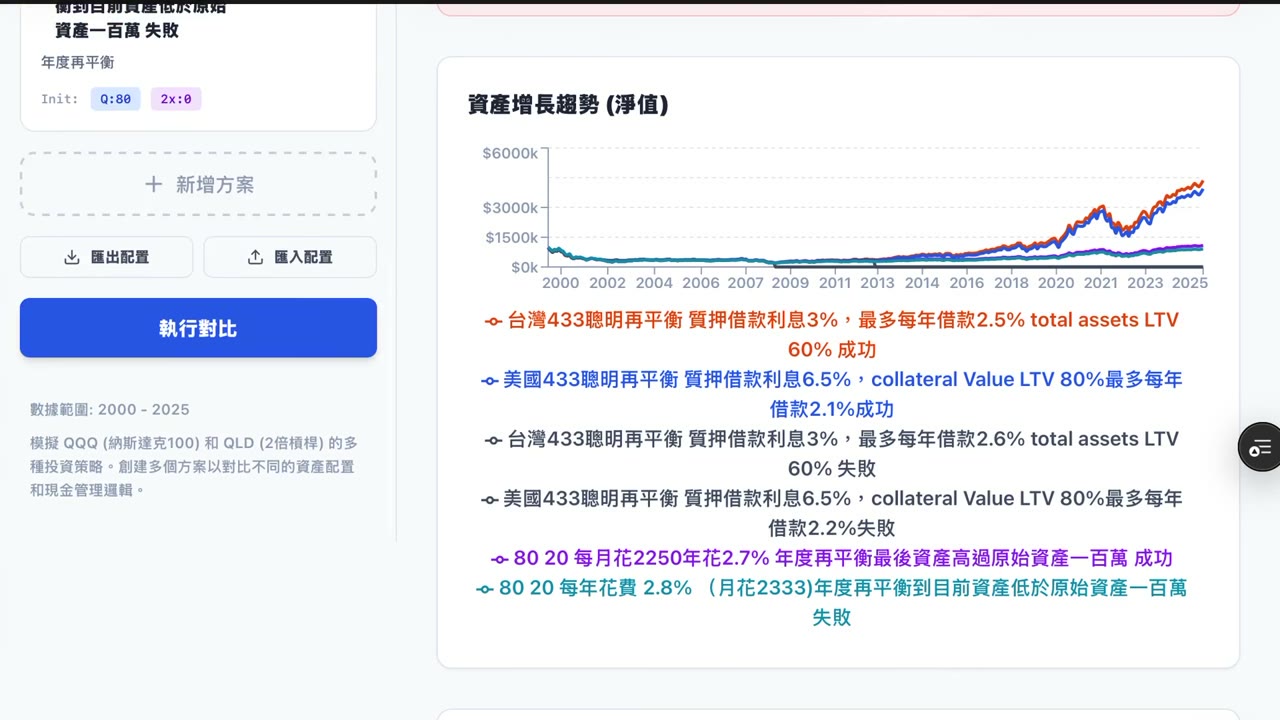
This video compares six Taiwan and U.S. 433 and unpledged 80/20 backtests, then shows how rebalancing, loan rates, LTV, collateral assumptions, and spending affect pass/fail results and ending assets.
10:04