00546
[You could have retired a long time ago, but you didn’t dare
Long
[You could have retired a long time ago, but you didn’t dare
This long-form Q&A covers investment information, consumption and parenting, an incomplete year-end transfer question, banking history, connected-car parking claims, retirement cash, QQQI, BOXX, and SGOV.
2:32:19
00617
How the 442 Allocation Evolved from Aggressive to Prudent
Short
How the 442 Allocation Evolved from Aggressive to Prudent
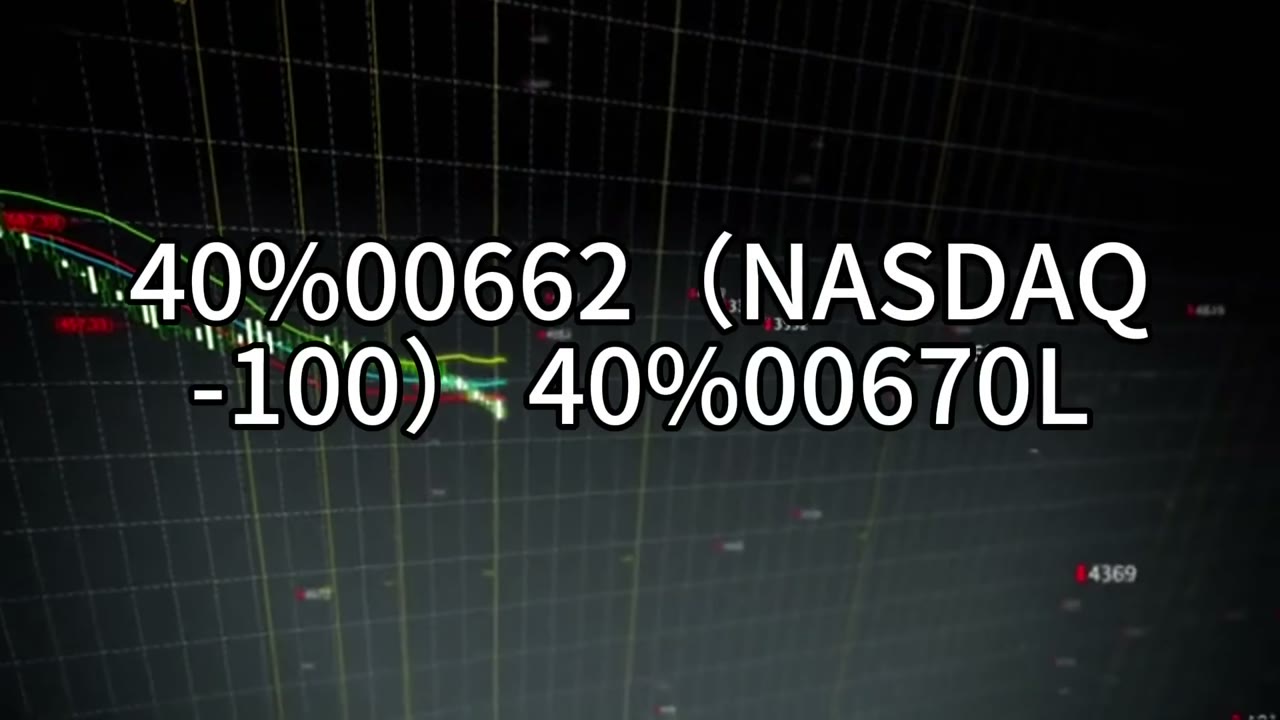
A student can add NT$3.5 million of mortgage debt and plans to invest NT$2 million in 40% 00662, 40% 00670L, and 20% 00865B. The video compares 4:4:2 with 4:3:3 and 4:2:4.
4:22
00617
Mortgage is not a cash machine: cash flow is the cornerstone of investment
Short
Mortgage is not a cash machine: cash flow is the cornerstone of investment
The video opposes borrowing against a home to invest entirely in QQQ when income is unstable, then relying on stock gains for mortgage and living costs. Cash flow is treated as the prerequisite.
2:54
00617
After the loan is paid off, can I lend it out again for investment?
Short
After the loan is paid off, can I lend it out again for investment?
The video asks whether a nearly repaid mortgage can be refinanced for investing, either next year or now through a replacement loan. The speaker proposes 70:30 or 5:1:4 allocations subject to affordability.
3:11
00617
Correct answers to overseas accounts, inheritance tax and asset allocation
Short
Correct answers to overseas accounts, inheritance tax and asset allocation
A retired Shenzhen teacher reports stable pension income, RMB6,000 monthly spending, and an Interactive Brokers account holding individual stocks, QQQM, and 30% cash. The video raises U.S. estate-tax concerns.
4:26
00616
Triple leverage is not a shortcut to financial freedom: how misallocation can bring assets to zero
Short
Triple leverage is not a shortcut to financial freedom: how misallocation can bring assets to zero
A 48-year-old with NT$15 million considers NT$5 million in TQQQ and NT$10 million in 00865B, rebalanced toward beta near 1. The video illustrates triple-leverage risk and compares three alternatives.
3:50
00616
The starting point for doubling assets: From conservative to proactive, a 16-year plan to reach 300 million
Short
The starting point for doubling assets: From conservative to proactive, a 16-year plan to reach 300 million
A 49-year-old dentist reports about NT$25.6 million in liquid assets and possibly NT$30 million after surrendering savings policies. The video models a NT$300 million goal over 16 years.
4:40
00616
Individual stocks are not a safety net: correct asset allocation can protect you in retirement
Short
Individual stocks are not a safety net: correct asset allocation can protect you in retirement
Two Taiwan public-school teachers report pensions near NT$60,000 each, no mortgage, NT$20 million in stocks, and a planned NT$10 million flexible mortgage. The video compares individual stocks with 00865B.
4:18
00616
What is true love? ──Starting from the struggle of a marriage
Short
What is true love? ──Starting from the struggle of a marriage
A husband married for more than a decade with two children describes repeated conflict, his wife’s exhaustion from family care, and a dispute over his proposed six-day baseball trip to Japan.
3:25
00615
Look at your future self from now and decide your destiny 30 years from now
Short
Look at your future self from now and decide your destiny 30 years from now
The video contrasts short-term trading with holding QQQ or 00662 over 30 years, using NT$1 million, a 10% assumed return, and NT$100,000 annual additions to illustrate compounding.
4:41
00615
The mortgage limit is high, but you don’t have to borrow all of it! How to safely plan funds and avoid future cash flow crises
Short
The mortgage limit is high, but you don’t have to borrow all of it! How to safely plan funds and avoid future cash flow crises
A couple nearing 50 reports NT$10 million invested and NT$50,000 monthly free cash flow. The bank offers NT$21 million at 3% for 30 years with a three-year interest-only period.
4:59
00615
The best allocation strategy and single trust planning for 30 million assets
Short
The best allocation strategy and single trust planning for 30 million assets
With about NT$30 million of liquid funds and NT$60,000 monthly spending, the video discusses a 70/30 allocation, a rental-property decision, and trust supervision for a single person without children.
6:07